

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Software development divides into 13 distinct disciplines, each with its own tooling, risk profile, and skill requirements.
- In a regulated financial environment, the type of developer you hire determines not just what gets built but whether it survives a compliance audit. A generalist full-stack developer and a security-aware backend engineer are not the same hire.
- Front-end, back-end, and full-stack development form the foundation of most fintech products, but the additions that actually differentiate financial software are API development, security, cloud, and mobile.
- AI and ML development have moved from experimental to operational in fintech. Real-time fraud detection, credit scoring, and transaction monitoring are now standard engineering problems, not research projects.
- The global software development market continues growing, but talent scarcity, particularly for compliance-aware fintech engineers, is making the right type of developer harder to find than the budget to hire them.
Software development isn’t one thing.
A backend engineer building a payment processing system, a mobile developer shipping a neobank app, and a security engineer hardening a KYC pipeline are all doing “software development”, but the skill sets, tools, and failure modes are entirely different.
Understanding the distinct types matters when you’re hiring, augmenting a team, or deciding which engineering capability to build in-house versus bring in externally.
Hiring for one skillset when you need someone else entirely is not only costly, but it may also lead to potential regulatory vulnerabilities.
Let’s look at the 13 types of software development, with particular attention to how each one shows up in fintech, where the stakes for choosing the wrong approach or the wrong developer are considerably higher than in most other industries.
At Trio, we have a variety of developers in our talent pool, pre-vetted for production fintech experience, so that they can be onboarded in as little as 3-5 days.
1. Front-End Development
Front-end development covers everything a user sees and directly interacts with. It refers to the visual layer, the navigation, the forms, and the feedback loops.
In web development, the core languages are HTML, CSS, and JavaScript, with frameworks like React (used by 46.9% of professional developers in the 2025 Stack Overflow survey, up from 39.5% a year earlier) dominating fintech web products specifically.
The fintech-specific pressure on front-end work is accessibility and trust.
A lending application or investment platform needs to feel credible and clear, or people will be hesitant to use your application.
On the other hand, an ambiguous UI on a loan application can quickly become a compliance problem.
Front-end engineers building regulated financial products also need to think about session timeout behavior, sensitive data masking, and accessibility requirements that don’t apply the same way in consumer retail apps.
2. Back-End Development
Back-end development powers what the user never sees. This includes things like servers, databases, APIs, business logic, and the infrastructure that makes the front-end work.
Popular back-end languages in fintech include Java, Python, Go, and Node.js, with Go increasingly preferred for high-throughput payment systems where latency is a hard constraint, not a nice-to-have.
Fintech back-end work carries a different risk profile than standard back-end development because issues like a bug in a payment processing engine can produce duplicate charges, failed settlements, or incorrect ledger entries that require manual reconciliation at scale.
Engineers who’ve built back-end systems for regulated financial products tend to approach data consistency, idempotency, and failure handling differently from those who haven’t.
3. Full-Stack Development
Full-stack development combines front-end and back-end work in a single role.
A full-stack developer can build across both layers, which makes them valuable for early-stage products and rapid iteration, like fintech teams that need to ship an MVP quickly before adding specialists.
However, there is a definite trade-off.
When a payment system needs to process thousands of transactions per second, or when a compliance team needs the audit trail architecture reviewed by someone who builds exclusively in that domain, a generalist full-stack developer is probably not the right choice.
Instead, we recommend that most growth-stage fintechs utilize full-stack developers for speed early on, and then hire specialists as the product matures and the compliance requirements become concrete.
4. Mobile Development
Mobile development covers applications built for smartphones and tablets. Mobile is often the primary product surface these days. Neobanks exist exclusively as mobile apps, and even traditional financial institutions now treat the mobile app as the main customer-facing channel.
Native mobile development for iOS uses Swift (or Objective-C for legacy systems), while Android uses Kotlin or Java.
Cross-platform frameworks like Flutter and React Native reduce development time by maintaining a single codebase for both platforms.
Flutter appears to have gained ground over the past two years, and its performance has improved enough that teams now use it for transaction-heavy screens where native was previously assumed. Treat that as a direction of travel rather than a benchmark, since most of the published comparisons are vendor-run.
Biometric authentication, secure enclave access and deep OS integration for payment features still work more reliably in native code, which is why plenty of neobanks run a cross-platform shell with native modules underneath.
5. API Development
API (Application Programming Interface) development creates the connection layer between software systems. This lets different applications talk to each other.
In fintech, examples include connecting payment gateways to merchant platforms, core banking systems to third-party analytics tools, and open banking APIs to licensed third-party providers.
PSD2 in Europe mandates that banks expose account data and payment initiation through APIs to licensed third parties.
Open Banking frameworks globally are built on the same premise.
6. Data Science Development
Data science sits at the intersection of software development and statistical analysis. Rather than building products, data scientists build models, systems that find patterns in data and generate predictions or classifications.
It is also the driving force behind fraud detection, credit scoring, and regulatory reporting.
The volume of data that financial systems generate makes data science both more powerful and more complex in fintech than in most other industries.
A fraud detection model for a payment processor might need to classify millions of transactions per day with sub-100ms latency. A credit scoring model might incorporate hundreds of behavioral signals from a user’s transaction history.
The engineering infrastructure required to train, serve, and monitor these models is its own discipline, which is partly why MLOps has emerged as a specialized role in financial services organizations.
7. Security Software Development
Security software development focuses on protecting systems, data, and users from unauthorized access and malicious activity.
It encompasses secure coding practices, penetration testing, vulnerability scanning, and the design of authentication and authorization systems.
In fintech, security is a design constraint that determines the architecture from the start.
PCI DSS governs payment card data handling, SOC 2 defines the security controls that service organizations must demonstrate, and GDPR and regional data protection laws constrain how personal financial data can be stored and processed.
An engineer who builds a payment system without accounting for PCI DSS scope creates compliance debt that can cost more to remediate later.
Related Reading: SOC 2 Compliance Engineering Support
8. Cloud Computing Development
Cloud computing development covers the design and deployment of applications on cloud infrastructure, AWS, Google Cloud, and Azure being the dominant platforms.
Cloud-native development using containers (Docker), orchestration (Kubernetes), and microservices has become the de facto architecture for fintech products that need to scale.
Regulated markets often require data residency in specific geographic regions. An EU-regulated fintech can’t simply route customer financial data through a data center in a jurisdiction that doesn’t meet adequacy requirements.
Developers need to understand both the infrastructure layer and the regulatory constraints that shape where data can actually live.
9. End-to-End Application Development
End-to-end application development covers the whole product cycle rather than one layer: requirements, architecture, build, test, release and the operational work that follows launch.
In financial products that means neobank apps, payment platforms, lending systems, wealth management tools and the compliance infrastructure behind them, usually built by a team that owns the outcome rather than a single discipline.
Timelines run longer than comparable consumer apps. A consumer product can ship a feature behind a flag and watch what happens. A lending product usually waits on a compliance review, a penetration test and, in some markets, a regulator's sign-off before the same feature reaches a customer.
10. Desktop Development
Desktop development covers applications that run on Windows, macOS, or Linux operating systems.
It’s less central to modern fintech than it was a decade ago; most new financial products are built as web apps or mobile apps rather than installed desktop software.
Where desktop development does appear in financial services is in institutional contexts, like trading terminals, risk management systems, and compliance monitoring tools that require deep integration with local hardware, custom peripherals, or offline capability.
Bloomberg Terminal is probably the most well-known financial services desktop application, but institutional-grade portfolio management and trade execution software in this space remains active.
11. Software Tools Development
Software tools development produces the infrastructure that other developers use to build software, IDEs, code editors, testing frameworks, CI/CD pipelines, and version control systems.
Most fintech engineering teams use tools built by others rather than building tools themselves.
The exception is internal tooling, like a custom compliance rule engine, a proprietary data pipeline for regulatory reporting, or an internal testing framework for payment flows that don’t have adequate coverage in off-the-shelf tools.
When a fintech reaches a certain scale, building internal tooling that matches the specific constraints of a regulated payment environment often becomes more cost-effective than adapting generic tools.
12. AI and Machine Learning Development
AI and ML development has become one of the most in-demand types of software development across industries, and fintech has adopted it faster than most.
Google's 2025 DORA report put AI adoption among developers at 90%, a 14-point jump in a year, with a median of about two hours a day spent using the tools. Stack Overflow's 2025 survey is more conservative at 84% using or planning to use them, which is a reminder that adoption and daily reliance are not the same measurement.
In fintech specifically, the applications have moved into the operational core. Fraud detection, credit scoring, AML transaction monitoring, and regulatory document classification are now standard ML engineering problems at financial institutions of all sizes.
ML engineers need to understand model training, feature engineering, validation methodology, and production deployment patterns that don’t appear in traditional software engineering curricula.
The fintech-specific layer adds regulatory requirements around model explainability, since decisions need to be auditable.
13. Embedded Systems Development
Embedded systems development builds software that runs inside physical hardware rather than on a general-purpose computer.
The engineering challenges that you’ll encounter in this category are distinct from application or web development, because embedded systems typically have very constrained memory, no or limited operating system, and real-time processing requirements.
In fintech, embedded systems development intersects directly with payment hardware, specifically the firmware running in a chip-and-PIN terminal, the software controlling an ATM’s cash dispensing mechanism, and the secure element software managing cryptographic keys in a contactless payment card are all embedded systems.
We’re seeing the market for this kind of payment hardware grow alongside the broader fintech market, and engineers who combine embedded development with payment security expertise are genuinely scarce.
Related Reading: Fintech Hiring Slowdown
Where These Categories Overlap
A numbered list of 13 disciplines suggests cleaner boundaries than the job market actually has, so it is worth naming where the lines blur.
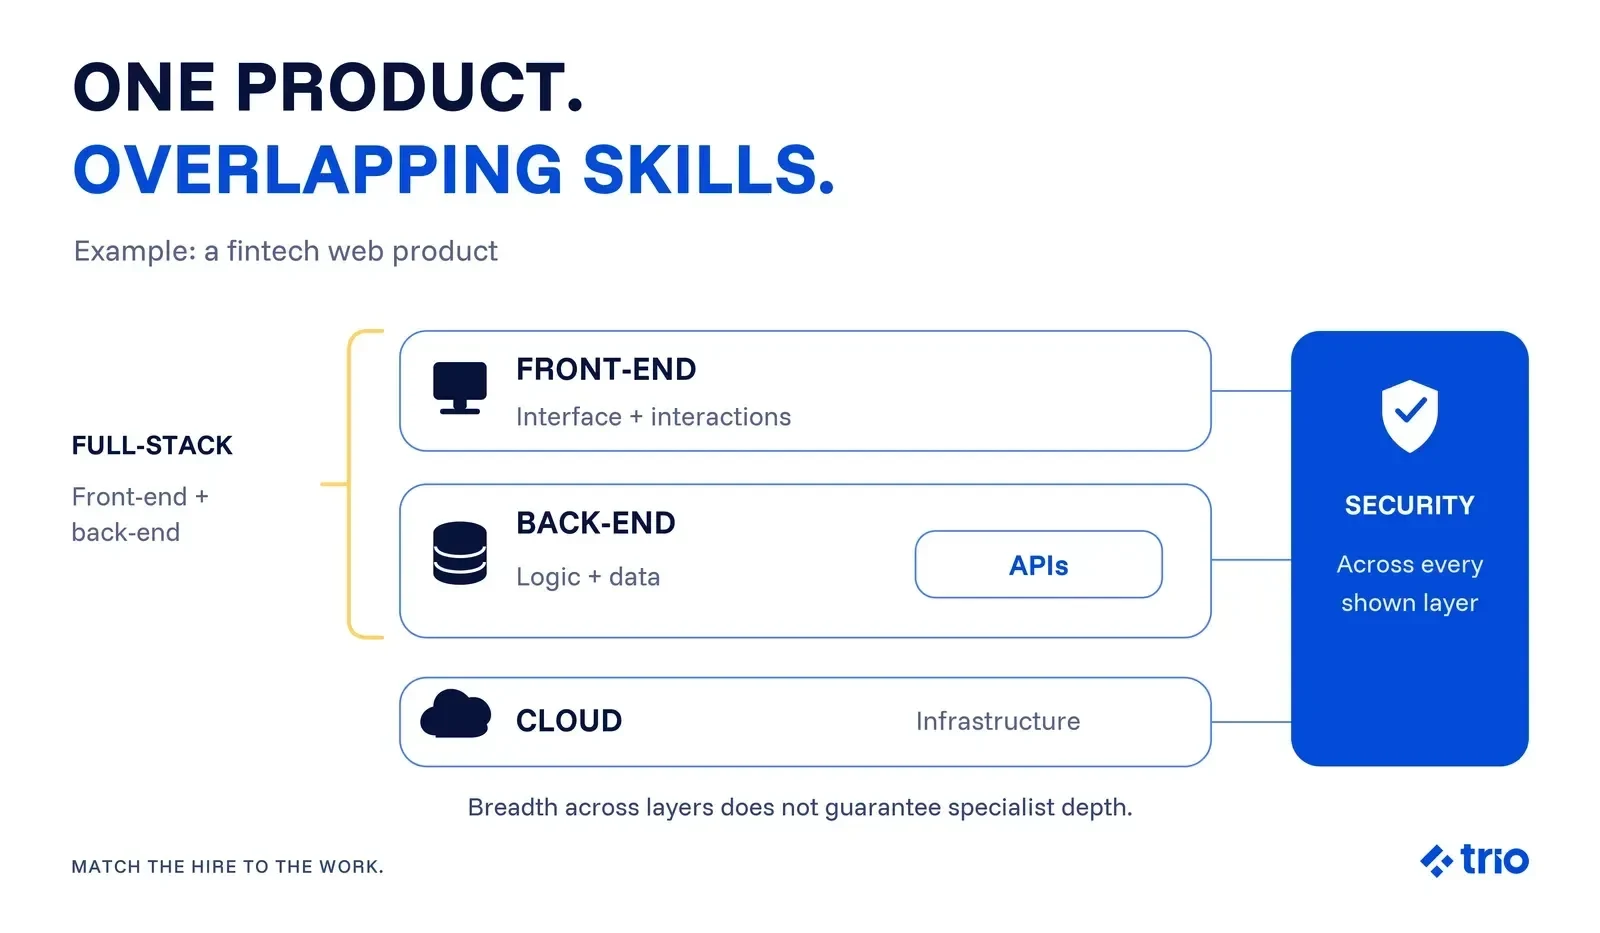
Full-stack is not a fourteenth skill. It describes someone who works across the first two, and the depth they reach in each one varies enormously between candidates.
API development usually sits inside a back-end role rather than beside it. Hiring separately for it makes sense at the scale where the API is the product, and rarely before.
Security is a property of every category above rather than a department. A security engineer helps, though a back-end team that writes raw SQL will keep producing work for them.
Data science and ML engineering get used interchangeably in job ads and are not the same work. One builds the model, the other keeps it serving under load and explains its decisions to an auditor.
Which Type of Software Development Does Your Fintech Team Actually Need?
Most fintech products require more than one type of development simultaneously. For example, a neobank app needs mobile development, back-end development, API development, and security software development running in parallel from day one.
The most common team-design mistake we see in fintech, especially in smaller startups, is treating software development as a single skill category when making engineering hiring decisions.
Hiring a generalist back-end developer to build compliance infrastructure, or a mobile developer to own the API layer, produces the kind of technical debt that surfaces during a compliance audit rather than during code review.
At Trio, we place pre-vetted fintech engineers across all of the disciplines above. These engineers have built in regulated financial environments and carry domain knowledge in the specific type of development your product requires.