

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Fintech app development carries a compliance layer that general mobile development doesn’t. GDPR, PCI DSS, AML, and KYC requirements need to be designed in from the start.
- Picking a specific niche (digital banking, lending, or insurtech) is what actually gets a fintech MVP shipped in a realistic timeframe.
- AI now touches nearly every category of fintech app, from fraud detection to personalized budgeting to credit decisions, and it’s increasingly treated as a baseline expectation.
- A fintech build needs developers who understand compliance implications alongside the code itself.
- Realistic development timelines run three to twelve months depending on scope and team size.
The fintech market is projected to grow to over $1.76 trillion by 2034 according to Fortune Business Insights, and considering the massive portion of regular app users who use their phones as their primary device, mobile is likely going to be a massive contributor to that growth.
However, if you are going to benefit from that growth, you need to create applications that offer smooth user interfaces and that handle user data securely. Any perceived breach of trust or unprofessionalism might encourage users to turn elsewhere.
In short, a successful fintech app balances user expectations, real regulatory demands, and a pace of change most other software categories don’t have to contend with.
Let’s look at the step-by-step process of fintech app development. If you need developers to ensure that your app is compliant and meets industry standards, we can assist.
What Is Fintech App Development?
Fintech app development, as the name suggests, means building mobile applications that deliver financial services. Some of the most common examples include mobile banking, payment apps, personal finance tools, lending platforms, insurance products, or crypto exchanges.
Many of these apps function as modern interfaces sitting on top of legacy financial infrastructure underneath, which is part of what makes the engineering work more involved than a typical consumer app.
Why Build a Fintech App Now
For a startup in the finance sector, mobile-first development costs less than standing up a traditional financial services operation. Focusing on building a fintech mobile app first greatly lowers the barrier to disrupting an established market.
In some cases, it’s also easier to iterate quickly and test with real users, especially starting from a focused MVP rather than trying to launch a full-featured product on day one.
For an enterprise, a fintech app is a way to keep pace with the market, modernizing how existing services get delivered while adding new ones, and taking advantage of the institutional trust that you already have.
Fintech Apps Worth Knowing
There are some great examples of successful fintech apps on the market.
Revolut built its early reputation simplifying foreign exchange before expanding into most core banking services. This company launched out of a startup incubator.
Chime grew by eliminating the fee structures that frustrate traditional banking customers, reportedly serving 9.5 million active members as of its Q4 2025 earnings.
Robinhood removed most investment fees and gamified the onboarding experience to lower the barrier for first-time investors.
Klarna built its growth around buy-now-pay-later, integrated directly into online checkout flows rather than requiring a separate app visit.
While there is definitely a case for super apps, notice how each of these succeeded by specializing deeply in one or two things rather than launching broadly. Expansion can happen later, as users request additional features.
The Fintech Market Worth Understanding First
Open banking, or letting third-party apps access financial data with consent, has expanded what banks can offer while raising the bar on security and data handling.
Embedded finance keeps growing too, with financial services showing up inside platforms that aren’t financial companies at all. This is the same pattern behind Klarna, which now shows up inside most ordinary online checkouts.
We’re also seeing a shift in previously cemented success patterns.
Traditional branch banking keeps losing ground to digital-first models. Outside of simply being convenient, the success of neobanks and similar products is driven by user demand for transparency, simplicity, and lower cost as much as by the underlying technology shift.
On the more experimental side of things, decentralized finance and blockchain-based tools remain an active area. We’re watching these trends very carefully to see where they land and are helping our clients prepare for changes going forward.
The Fintech App Development Process
While the exact development process depends on your specific app, there is a general process you can follow to ensure nothing falls through the cracks.
Step 1: Define your niche and target market
Solving a real problem well beats covering broad ground badly. It also gives you something to market to clients.
Digital banking, payments, budgeting, robo-advisory, P2P lending, insurtech, regtech, and crypto are all viable directions.
Regardless of what the actual direction is, picking one deliberately, based on real market opportunity, shapes everything that follows.
Step 2: Conduct regulatory and compliance research
This is where fintech development genuinely diverges from building a normal app.
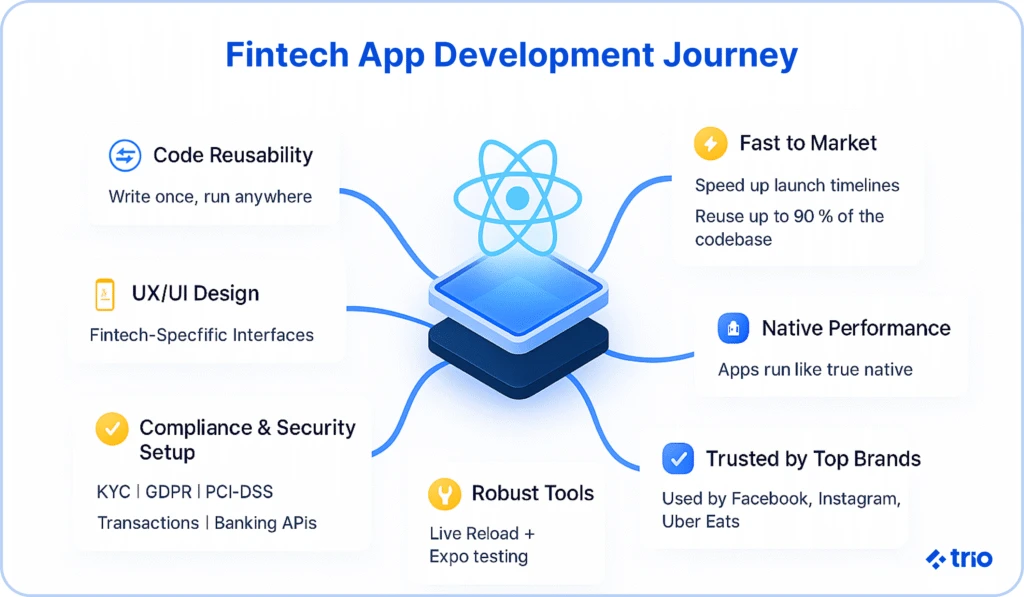
Requirements like GDPR, PSD2, AML, and PCI DSS apply from day one, and a fintech-experienced partner can flag obligations a team might not think to check for until they’ve already scaled them.
KYC processes, secure data handling, and consent management for third-party integrations all need real design attention. Getting this wrong is far more expensive to fix later than simply setting yourself up for success from the start.
Issues can also mean serious fines or lost user trust that’s hard to earn back.
Step 3: Choose a monetization strategy
Essentially, any way you can think of to monetize is fair game, but keep in mind that while transaction fees work for traditional banking and trading products, they can create a real barrier to adoption.
From what we have seen, subscriptions and tiered plans suit budgeting tools well.
Premium feature upselling, referral programs, and (handled transparently, with real consent) data monetization are all viable alternatives depending on the product.
If your product is in the B2B sector, then API access, or charging other companies to build on a platform, is its own monetization path worth considering.
Step 4: Define MVP features
Building everything at once isn’t realistic for most teams, especially if you are just starting out. Fortunately, it isn’t necessary either.
A focused MVP with the most important features, typically a clean UI with real-time dashboards, secure verification, solid encryption, and some degree of AI-driven personalization, ships faster and gets real user feedback sooner than a fully-loaded version ever could.
This has the added benefit of giving you the ability to adjust your approach and minimize your overall risk.
Step 5: Select your tech stack
Match the mobile framework to the language skills your team needs. Flutter uses Dart, so JavaScript or Python experience alone should not be treated as Flutter expertise.
When planning your team, assess the frontend- the app interface users interact with- separately from the backend services it connects to. Confirm the skills needed for each before commissioning the build.
Cloud infrastructure is standard as well, and typically runs on AWS or Google Cloud, containerized with Docker and Kubernetes.
Third-party APIs, already built to be compliant, are often the more practical starting point over building payment or identity infrastructure from scratch.
Once you have more funds available, you can consider replacing API services to decrease vendor risk.
Step 6: Build or augment your development team
Hiring each developer individually is possible but resource-intensive.
You will have to move through an extensive process that involves portfolio reviews, interviews, and onboarding. The real risk of a costly mis-hire adds up.
Staff augmentation through an experienced partner like Trio compresses this considerably, connecting a team with developers who already have relevant fintech project experience, without the commitment of a full-time hire whose future workload isn’t guaranteed yet.
Step 7: Develop, test, and launch
Our developers have commented that Agile methodologies suit fintech development well, given how much requirements tend to shift as compliance research and user feedback both surface new information.
Automated testing (simulated user interaction) paired with real beta testers gives more complete coverage than either approach alone. Both are pretty much considered to be industry standards at this point.
Reliability, low latency, and error-free transaction handling are also critical, and app store compliance requirements need attention before submission.
Step 8: Gather feedback and iterate
Once your app is live, pay attention to reviews, in-app feedback, and analytics. These can tell you what to build next.
A/B testing tends to work better than intuition alone for fintech UX specifically, since financial decision-making under pressure doesn’t always behave the way product instinct predicts.
How Much Does Fintech Mobile App Development Cost?
Budget planning for a fintech app starts with a realistic range, not a single number pulled from a vendor's sales page.
MVP builds with core account features and basic transaction tracking tend to land around $60,000.
A full, compliance-ready platform with payment processing, fraud monitoring, and multi-region support often runs $300,000 or more.
Mid-complexity builds, a single-currency app with one or two integrations, generally fall somewhere between $45,000 and $250,000.
A few factors shift a project up or down that range:
Integration count: each banking API, KYC provider, or payment gateway adds development and testing time.
Compliance scope: a build that only needs GDPR coverage requires less than one that also needs PCI DSS and SOC 2.
Platform strategy: separate native iOS and Android apps cost more upfront than a single cross-platform build.
Design complexity: a highly custom interface takes longer to build than one assembled from a proven component library.
Team structure changes the math as much as feature scope does.
Hiring US-based fintech engineers directly tends to run $120,000 to $150,000 a year per developer, plus recruiting fees that typically add 15 to 40 percent on top. Staff augmentation through a firm like Trio runs $40 to $90 an hour, with no recruiting or termination costs layered in.
None of this replaces a scoped estimate. The fastest way to get one that reflects your compliance requirements and feature list is to request a consult.
Future-Proofing a Fintech App
Technical debt accumulates fast in a space that changes as quickly as fintech does, and staying competitive means continuously revisiting existing features.
AI and automation increasingly handle routine tasks and personalization work that would otherwise consume real engineering time.
If you are planning for expansion into new regions, you will also need to plan for different regulatory regimes and currencies.
Continued attention to accessibility, screen readers, and alternative input methods keeps a product usable for the widest possible audience as it grows.
Choosing a Fintech App Development Partner
One of the best ways to ensure success is to look for a partner with genuine, provable experience in a comparable product.
When evaluating a potential company, real case studies and references matter a great deal, since fintech-specific judgment is hard to fake convincingly in a sales conversation.
At Trio, our developers have worked on several high-stakes fintech projects. To see if they are the right fit for you, request a consult.