

 Read Client Stories




 Alex Kugell
 Key Takeaways
- The 2025 GENIUS Act gave stablecoins a clear US regulatory framework for the first time, and banks are responding by pursuing banking-like charters and treating them as core infrastructure.
- Consumer trust is real but conditional. Most users would open a stablecoin wallet if their own bank or fintech app offered one.
- Central bank digital currencies have moved slower than expected, and the obstacle is largely political, since transparent, state-issued digital money raises real privacy concerns.
- The European Central Bank warned in 2026 that stablecoin growth could pull deposits away from traditional banks.
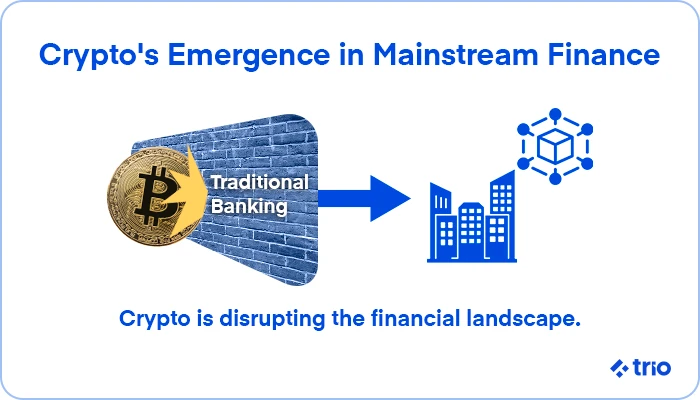
Cryptocurrency stopped being a fringe interest years ago and has become a popular investment for a variety of different people and institutions.
What’s changed more recently is that it is no longer speculative trading. Stablecoins are quietly becoming real payment infrastructure, with banks and regulators responding accordingly.
As the cryptocurrency landscape shifts, so do the regulations around it. Let’s look at everything you need to know about cryptocurrency and fintech, including how banking has been transformed, and the talent you need on your team to ensure compliant architecture.
If you need fintech talent to help you build your applications, we can help.
How Fintechs Are Actually Adopting Crypto Now
A few years ago, fintech was associated with trading and speculation.
In 2026, it increasingly means stablecoins functioning as payment rails. We see them used in treasury operations, cross-border settlement, and B2B payouts.
The scale is another issue. Stablecoin transaction volume grew 72% in 2025 to an estimated $33 trillion, and forecasts estimate they will make up roughly 3% of all US dollar payments in 2026.
Why Regulatory Clarity Changed the Calculus
The 2025 GENIUS Act gave stablecoins a formal legal definition in the US for the first time.
Now, any banks, fintechs, and multinationals moving into the space can do so with a confidence that wasn’t there when the regulatory status was genuinely unclear.
In the EU, MiCA is pushing in a similar direction, requiring stablecoin issuers to hold a meaningful share of reserves with EU commercial banks and pursuing tighter disclosure and stress-testing requirements.
You need to consider these established frameworks and how they may shift in the future when building your applications.
What Banks Are Actually Doing About It
A 2026 survey from BVNK found that 77% of users who hold or intend to hold stablecoins would open a stablecoin wallet specifically through their existing bank or fintech app, rather than a crypto-native platform.
That means that people largely want stablecoins inside the tools they already trust, not a new app to learn.
Banks aren’t ignoring this.
Regulators are taking the shift seriously. Stablecoin growth in the euro area, for example, could weaken the central bank’s policy influence and pull deposits away from traditional lenders.
Banks are positioning themselves to become stablecoin issuers and custodians themselves specifically because sitting out risks losing deposits to the infrastructure replacing part of their own function.
Central Bank Digital Currencies Haven’t Moved as Fast as Expected
Several countries have piloted central bank digital currencies. China’s digital yuan and Nigeria’s eNaira are just a couple of popular examples.
However, broader adoption has moved more slowly than we previously expected, and the primary obstacles were more political than technical.
Cash allows anonymous value transfer. A fully transparent, state-issued digital currency raises real privacy and civil-liberty questions.
Commercial stablecoins, by contrast, are already live, integrated, and embedded in real economic flows, which is a large part of why they continue to dominate near-term cross-border settlement activity even in markets where a CBDC pilot technically exists alongside them.
What This Means for Building on This Infrastructure
Integrating stablecoin rails today means building against a real, if still evolving, regulatory framework.
This changes the risk calculus for a serious build.
We have found that embedding stablecoin functionality inside an existing trusted product beats launching a standalone crypto-native app for most use cases.
And the reconciliation and compliance discipline that applies to any payment rail applies here too. A stablecoin transaction still needs to reconcile against a source of truth and produce an audit trail a regulator can follow.
Building this well requires engineers who understand both the crypto-specific mechanics and the standard fintech discipline: reconciliation, ledger design, and compliance evidence.
At Trio, we have fintech specialists with production experience building the compliant architecture you require. These developers are pre-vetted, so you can get the right people in your team in 3-5 days.