Hire by Technology
SERVICES


The FBI logged $893 million in losses from US complaints with an AI connection during 2025, the first year it tracked artificial intelligence as a category at all.
That number tells us a lot about how AI has arrived in financial fraud as an attacker capability, and that it is moving before the defense is catching up.
Voice cloning, synthetic identity generation, and deepfake onboarding attempts all scaled first.
Below are twelve companies using AI for fraud detection in fintech, grouped by the problem each one actually solves, plus an honest look at what these systems still get wrong.
At Trio, our developers have extensive experience integrating technologies like AI into production applications to improve real-time fraud detection.
Three things converged recently, and they compound to make AI fraud detection more urgent than ever before.
The biggest issue here is that an attacker, attempting something like running a voice clone, needs it to work once.
A bank or fintech needs its detection to work every time, across millions of legitimate interactions, without declining the customers who are genuinely who they say they are.
From what we’ve seen in production environments, most platforms run the same pipeline: ingest the event, enrich it with context, score it, decide, then learn from the outcome.
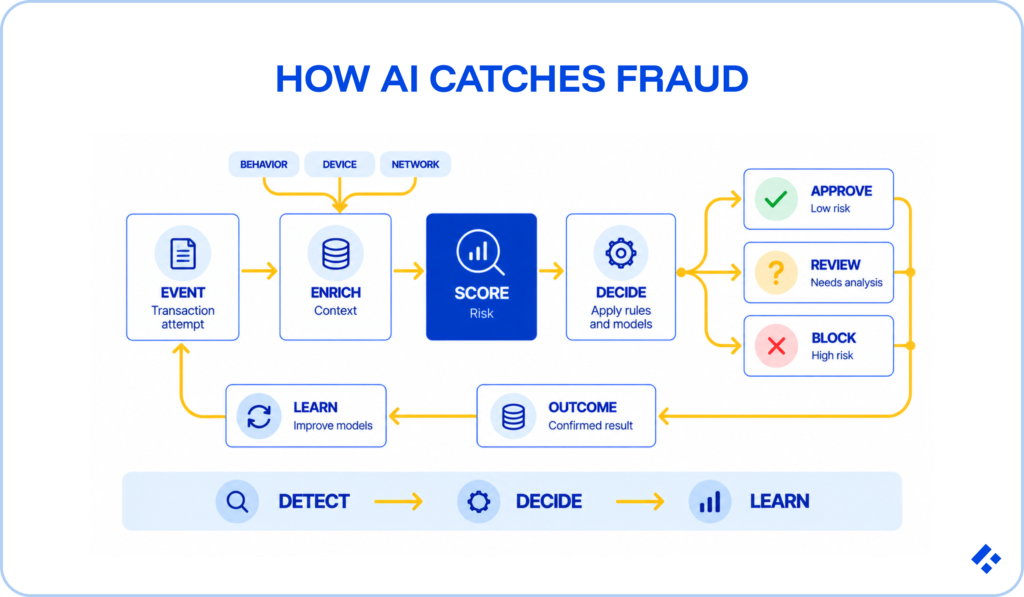
What ultimately varies is the signal.
Most serious platforms that we have utilized run several of these together, and no single technique carries the load.
If your system is relying only on supervised learning, it has a predictable blind spot, and one relying only on anomaly detection generates alert volumes nobody can work through.
Feedzai is the strongest enterprise option and is used by large banks and payment processors to score transactions across the customer lifecycle.
The company raised a $200 million Series D led by KKR in 2021, pushing its valuation over $1 billion.
Feedzai's position comes from breadth.
It handles payment fraud, account takeover, merchant risk, and anti-money laundering on one platform, which matters when a bank wants a single risk view rather than four vendors reporting separately.
Their case management and governance tooling is built for institutions that have to show a regulator how a decision was reached.
Featurespace built ARIC, an adaptive behavioral analytics platform that models each customer's normal behavior individually rather than scoring against population-wide rules.
Visa announced its acquisition in September 2024, in an undisclosed deal UK outlets reported at around $1 billion.
The company’s approach addresses a specific weakness in threshold-based systems.
A £5,000 transfer, for example, is highly unremarkable for one customer and wildly out of character for another. A universal rule will just get both wrong.
Adaptive behavioral modeling is what will give it a reasonable shot at genuinely new fraud, too, since it detects deviation rather than matching a known pattern.
Sitting inside Visa now changes its distribution considerably.
Sardine built its platform specifically for fintechs rather than adapting something from banking. This also shows in how it is sold and integrated.
Founded in 2020 by risk and compliance people from Coinbase, Revolut, Uber, and PayPal, it has raised around $145 million, including a $70 million Series C.
Two things have stood out to us here.
Its device intelligence and behavioral biometrics layer profiles billions of devices, and it operates a fraud data consortium covering more than 6.5 billion devices, 440 million consumers, and 3.4 million businesses.
That shared visibility is what lets it recognize a mule account the first time it appears in your portfolio, because it has already appeared in someone else's.
The second thing our developers have commented on is design philosophy: catch the signal at the moment of payment, then reuse it for AML rather than running two separate systems over the same data.
Clearly this has been successful, since it secured partnerships including Modulr in 2026 and reports over $1.8 trillion in transaction volume protected.
It seems to be the strongest fit for neobanks, crypto platforms, and embedded finance products.
NICE Actimize runs fraud and financial crime detection across a large share of tier-one banks.
The company carries the usual incumbent trade, with deep capability, extensive regulatory coverage, long implementation timelines, and a user experience, all of which tend to reflect its age.
Unit21 approaches the problem from the analyst's side rather than the model's. Its founder worked on risk and fraud systems at Affirm, and the product shows it, with a no-code rules interface and a case management experience built for the people who actually work alerts.
That can matter a great deal in production.
A platform generating excellent alerts into a bad investigation workflow produces a backlog. The difference between a team resolving cases in minutes and one taking days is usually tooling rather than model quality.
Unit21 raised around $45 million in Series C funding and suits fintechs that want control over their own detection logic without an engineering release for every rule change.
Hawk combines anti-money laundering and fraud detection with explainable AI as a core design choice rather than an added feature.
The explainability position is a massive differentiator in Europe, where regulators ask institutions to justify automated decisions.
A model that flags a transaction without being able to say why creates a compliance problem that essentially cancels out its accuracy advantage.
Alloy, which we have already briefly mentioned, sits at onboarding.
Their product involves orchestrating identity verification across multiple data providers and letting risk teams build decisioning logic without integrating each vendor separately.
The value is partly in the orchestration itself.
Identity data quality varies enormously by market and by provider, and routing between them based on what you are trying to verify produces better outcomes than committing to one.
Alloy also extends into ongoing monitoring, which catches the synthetic identity that would otherwise have passed onboarding cleanly and created issues later on.
Sumsub handles identity verification and KYC with particular investment in deepfake and injection attack detection, which has become a growth area in identity fraud.
Its own research put deepfakes at 11% of first-party fraud cases in 2025, a 245% year-over-year increase.
Detecting a synthetic face or a video injected directly into a verification flow is a different technical problem from checking a document, and vendors that only solve the second one are exposed.
Persona offers configurable identity verification with a focus on letting teams build their own verification flows rather than accepting a fixed one.
We have found that it’s quite useful where different products or risk tiers inside the same company need different levels of friction.
BioCatch specializes in behavioral biometrics, analyzing how a user physically interacts with a device in terms of things like typing rhythm, mouse movement, how a phone is held, and hesitation patterns.
The strongest application we’ve seen here is detecting scams in progress.
Someone being coached through a transfer by a fraudster on the phone behaves measurably differently from someone making a routine payment, with longer hesitations and unusual navigation.
That signal catches authorized push payment fraud, which every transaction-level check passes because the customer is genuinely authorizing it.
Quantexa builds contextual decision intelligence through entity resolution, connecting fragmented records into a single view of a person, business, and their relationships.
This is the tooling that is usually a big part of surfacing fraud rings.
Individually, ten accounts each moving modest amounts look unremarkable. Resolved into a network sharing addresses, devices, and counterparties, the pattern becomes obvious.
Network analysis is also what makes mule detection tractable, since mule operations deliberately stay below per-account thresholds.
If your fintech is touching crypto at all, Chainalysis provides blockchain analytics tracing funds across addresses and identifying wallets associated with sanctioned entities, scams, and illicit activity.
As stablecoin settlement moves into mainstream payment flows, on-chain screening stops being a crypto-specialist requirement and becomes a payments one.
Here’s a practical checklist to help you choose the right fraud detection for your product, ordered roughly by how often each one turns out to be decisive:
A model that declines a transaction without producing a reason creates two problems at once.
First, it creates an operational issue, since an analyst cannot investigate an alert unless they know which signals fired. This means they now have to investigate further, alert handling time rises, and the queue grows.
The second problem is a regulatory one, and carries more weight.
Financial regulators increasingly expect institutions to explain automated decisions affecting customers, particularly adverse ones. A deep learning model delivering a slightly better AUC score while producing no interpretable output can be the wrong choice even when it is technically more accurate.
This is why several vendors here lead with explainability rather than raw performance. It is also why gradient-boosted trees remain common in production fraud systems despite flashier alternatives existing.
AI isn’t perfect yet, and probably won’t be for a really long time. Knowing what issues you potentially need to look out for can help you prepare.
Choosing a vendor completes maybe half the work, and the remainder consistently gets underestimated.
Data plumbing comes first, since models need features computed from live event streams, and a velocity signal calculated from a warehouse table refreshed every five minutes is useless.
Real-time feature computation is a streaming engineering problem before it is a modeling one.
Once that is done, it’s a good idea to look at shadow mode before enforcement.
To do this, you will need to run new models in parallel with the existing system, logging decisions without acting on them, for at least a couple of weeks. You can then compare output against confirmed fraud before anything blocks a payment.
We have also found it best for response playbooks to be defined up front, allowing you to set out which scores trigger automatic declines, which trigger a customer challenge, and which go to an analyst. Deciding this during your first incident goes badly.
Finally, the labeling loop needs an owner. Confirmed fraud and confirmed-genuine outcomes have to reach training data reliably.
Teams building this usually need an unusual mix of streaming data engineering, applied machine learning, payments domain knowledge, and enough regulatory literacy to know which questions to ask before architecture gets fixed.
Most teams discover partway through a build that the hard part was never the model. Real-time feature computation, idempotent reconciliation, sanctions screening, and a labeling loop that actually closes all take longer than selecting a vendor.
At Trio, we place fraud detection engineers and KYC and AML developers who have built and maintained these systems inside regulated financial institutions, available through staff augmentation or as a dedicated team.
If you are scoping a fraud detection project or evaluating platforms, request a consult.