

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Microservices let fintech teams scale individual services, like payment authorization or fraud checks, independently instead of overprovisioning the whole platform.
- Splitting a workflow into services doesn't make it atomic. Sagas coordinate local transactions with compensating actions, and recovery can leave temporary inconsistency while someone investigates.
- The architecture pays off fastest where regulation and traffic actually concentrate, like KYC, payment processing, and fraud detection, where isolation and independent scaling matter most.
- Adoption is widespread but not frictionless; most teams that move to microservices report real gains, and a meaningful share also report a slower-than-expected path to ROI in the first year.
- Domain-driven design, not org charts or technical convenience, should decide where service boundaries sit. Splitting along team structure instead of business domains is a common and expensive mistake.
When you think about what makes fintech move so quickly (new payment apps, instant lending platforms, and digital-first banks), there’s one thing these players usually have in common: flexibility.
Under the surface, that agility often comes from a microservices architecture.
Instead of relying on one massive, tightly coupled codebase, fintech companies are breaking systems into smaller, independent services that can scale, update, and deploy without dragging the entire platform down.
In an industry where milliseconds matter, and regulations never stop changing, microservices can make or break how efficiently a business adapts. That’s why you need to understand what they are and how they work.
If you need skilled fintech specialists with software development experience in similar projects, we can help you find the right people in a couple of days, not months, and connect you with them through cost-effective hiring models like staff augmentation.
But before you consider hiring, let’s unpack how microservices architecture supports scalability in financial services, the challenges of implementation, and why so many fintech teams are embracing it as the foundation of their long-term digital strategy.
Understanding Microservices in Financial Services
Microservices architecture is a practical response to how software has evolved and how fintech demands have outgrown traditional systems.
What Are Microservices?
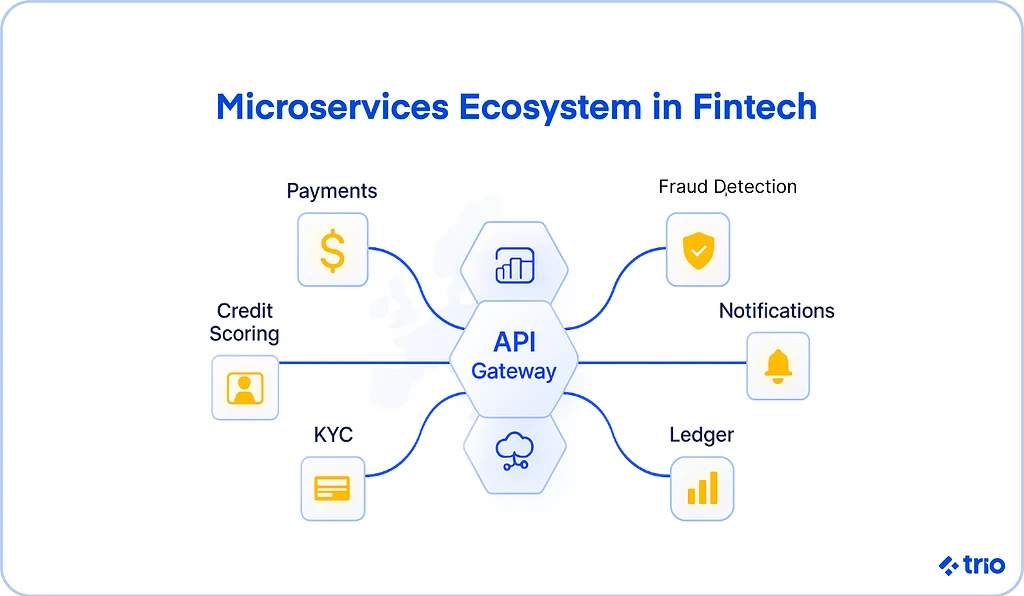
In simple terms, microservices split applications into smaller, self-contained components that handle specific business functions.
A lending platform might have separate services for credit scoring, document verification, and payment processing.
Each service operates independently, communicates through APIs, and can be deployed or scaled without impacting the rest of the system.
This structure contrasts sharply with monolithic architectures, where everything lives in a single codebase.
Monoliths can be easier to start with, but as fintech applications grow and regulations shift, they often become slow to update and difficult to scale.
Engaging experienced fintech engineers early in your architecture process helps avoid technical debt that can be costly to resolve later. Outsourcing from regions like LATAM expands access to specialized talent and keeps costs manageable for growing companies.
Core Principles of Microservices Architecture
Microservices rest on a few foundational principles that make them so adaptable for fintech systems:
Decoupled Components and Independent Deployments: Each service functions on its own lifecycle, meaning updates can happen without interrupting other parts of the system, reducing the risk of something going wrong with changes.
API-Based Communication and Lightweight Containers: APIs act as bridges between services, often containerized in tools like Docker or Kubernetes for predictable performance.
Continuous Delivery and Fault Isolation: Teams can deploy updates quickly while isolating failures, ensuring that if one microservice fails, others keep running.
These ideas align closely with how financial institutions want to operate: agile, reliable, and auditable.
Monolithic vs. Microservices: A Quick Comparison
Think of a monolith like a single large bank branch handling everything, from customer onboarding to risk management to payments.
If one process slows down, the entire operation does.
Microservices, in contrast, resemble a network of specialized branches that each handle one function efficiently.
For growing companies in the financial services industry, this difference can be transformative.
We have seen how it enables faster updates, continuous innovation, and a more responsive approach to compliance and customer needs.
Benefits of Microservices in Fintech
The fintech industry changes fast. Regulations shift, users expect real-time services, and transaction volumes can spike overnight.
Microservices architecture helps companies keep up without constantly rebuilding their systems.
Scalability and Load Management
Scalability is often the biggest reason fintech teams migrate to microservices.
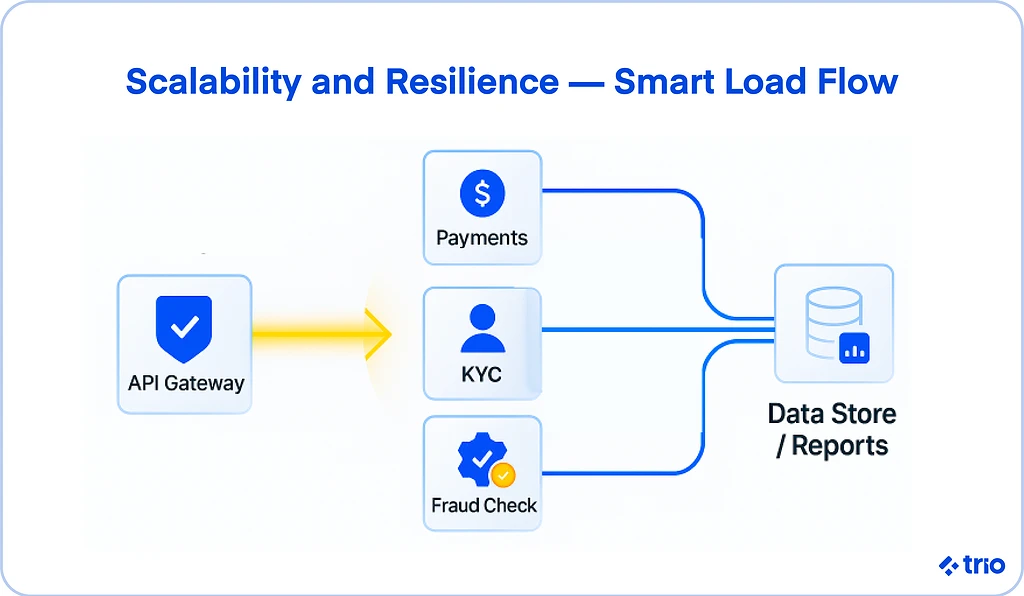
Each service can scale horizontally, meaning you can add more instances of just the parts that need extra power, such as payment authorization during peak shopping seasons.
By distributing workloads across microservices, fintech applications reduce bottlenecks and maintain stability under stress. That reduction depends on correct workload partitioning and realistic traffic modeling, not the orchestration tooling alone.
Systems like Kubernetes automate this scaling, letting teams allocate resources dynamically instead of overprovisioning infrastructure.
Faster Time-to-Market for Financial Products
In fintech, being first to market can mean everything. You can build a customer base and build a reputation before your competitors enter the market.
Microservices make it easier for development teams to roll out new products or features independently. A new fraud detection module, for example, can go live without waiting for the next full platform release.
This modularity supports shorter development cycles, experimentation, and continuous delivery, all critical advantages in a competitive financial services environment.
Enhanced Security and Compliance Monitoring
Security in financial systems is never optional, and microservices can strengthen it, making it a big part of reducing risk.
Segmentation means a breach in one component doesn’t automatically compromise the entire system.
It also makes regulatory compliance easier by letting teams isolate sensitive workloads (like KYC verification or payment data) and apply stricter controls only where necessary.
Each service can log and audit transactions independently, which simplifies traceability during compliance reviews.
Improved Fault Tolerance and Resilience
When a monolithic app crashes, everything stops.
With microservices, failure in one service doesn’t necessarily ripple across the system. Circuit breakers and retry mechanisms contain errors before they spread, maintaining uptime even during partial outages.
This stability and reliability are major factors in customer trust.
A few minutes of downtime in a payments platform can cost millions and damage a reputation.
Easier Maintenance and Team Autonomy
Microservices also let small, focused teams take ownership of individual services.
Developers can work in parallel using different programming languages or frameworks suited to each service’s function.
Maintenance becomes easier because teams fix or update only what they own, improving overall efficiency and morale.
Scalability in Fintech Solutions
Payment systems, trading apps, and neobanks face unpredictable workloads that can grow exponentially. Creating a scalable payment infrastructure is essential for the longevity of your firm.
Addressing legacy system limitations after the fact is often expensive, and by that point, system reliability and user trust may already have been impacted. Early architectural planning is crucial for sustainable scalability.
Why Scalability Matters in Financial Services
Transaction spikes are common in finance.
Think of Black Friday for digital payments or sudden interest-rate shifts affecting trading volumes.
Systems must handle these peaks in real time without collapsing or slowing down.
Scalability also enables global expansion. As fintech organizations move into new regions, they must support multiple currencies, languages, and regulatory frameworks, all while keeping performance consistent.
How Microservices Enable Elastic Scalability
Microservices architecture gives teams the tools to scale elastically, meaning resources adjust automatically to meet current demand. This happens through:
Horizontal Scaling and Container Orchestration: Platforms like Kubernetes and Docker allow developers to scale services independently, keeping costs aligned with usage.
API Gateways and Event-Driven Architectures: Gateways route traffic intelligently, while event-driven systems process transactions asynchronously for smoother performance.
Load Balancing, Service Mesh, and Observability Tools: These help monitor system health and distribute workloads evenly to maintain reliability under pressure.
Together, these mechanisms create fintech systems that can handle rapid growth without compromising service quality or compliance.
Implementing Microservices Architecture in Fintech
Transitioning from monolithic systems to microservices requires careful planning. IFavor gradual adoption over rewriting everything at once..
1. Assess Current Architecture and Pain Points
Start by identifying bottlenecks; maybe your payment processing is slowing down during high traffic, or compliance checks take too long.
Those problem areas often signal where microservices will add the most value.
2. Define Service Boundaries and APIs
Clearly define each service’s purpose and data flow.
APIs become the contracts between services, so precision here prevents confusion later.
3. Choose Technology Stack and Deployment Tools
Select technologies that fit your team’s expertise and compliance needs.
Docker and Kubernetes are industry staples, but fintech organizations might also rely on AWS ECS, Azure Kubernetes Service, or Google Cloud Run for deployment flexibility.
4. Establish CI/CD Pipelines and Monitoring
Automated pipelines keep updates frequent and safe.
Pair that with monitoring tools like Prometheus or Grafana for real-time observability and alerting.
5. Ensure Compliance Integration From Day One
Compliance isn’t something to bolt on later.
Incorporate regulatory requirements like GDPR or PCI DSS from the start by tagging and securing sensitive data appropriately.
Key Challenges in Deployment and Maintenance
While microservices bring scalability and agility, they also introduce complexity that fintech teams can’t ignore.
Data Consistency and Distributed Transactions
When a financial workflow spans services, distinguish local atomicity from cross-service consistency.
A local database transaction can commit all its changes together, but independently committed service transactions do not automatically form one atomic operation.
A saga coordinates local transactions and uses compensating actions when later steps fail, and temporary inconsistency can remain while recovery runs. Before splitting a workflow, identify which business rules actually require an atomic transaction and whether your proposed service boundaries can preserve them.
Event sourcing, on the other hand, records changes as an append-only event history that state can be reconstructed from. It does not, by itself, make a workflow atomic across services.
Think about a lending application with separate services for application status and review-task assignment. If the applicant cancels mid-process, the application service records the cancellation, and the review service cancels the pending task if its current state allows it.
If either step fails, that service owner needs to investigate, not the other team. The lesson here is that someone has to own each layer of your ledger system, and compensating commands need to be safe to run more than once.
Security, Authentication, and Authorization Across Services
With multiple services comes multiple access points.
Ensuring secure communication through token-based authentication and encrypted channels is essential.
Centralized identity management solutions can help maintain security without slowing performance.
Cross-Service Communication Latency
Microservices talk to each other frequently.
Each call adds latency, which can impact real-time transactions.
Optimizing APIs, caching, and using asynchronous messaging queues can reduce these delays significantly.
Regulatory and Audit Complexity
Decentralized systems have their use cases, but they can complicate audits.
Every service may generate its own logs, which need to be collected and correlated.
Fintech companies often deploy unified logging tools like the ELK stack (Elasticsearch, Logstash, Kibana) to keep audit trails complete and compliant.
When those logs need to reconcile against actual settled funds rather than just explain a request. You need the matching logic and exception handling that keeps the two in sync.
Best Practices for Fintech Microservices Development
A successful microservices environment is built through deliberate design and consistent maintenance.
Domain-Driven Design (DDD) for Financial Systems
DDD helps teams model microservices around real business domains like payments, onboarding, or account management.
It ensures services align with business functions and interfaces rather than arbitrary technical divisions.
Using API Gateways and Circuit Breakers for Fault Tolerance
API gateways manage traffic flow and protect backend services. Circuit breakers detect failing components and prevent system-wide cascades.
This is crucial for maintaining uptime in financial systems handling continuous transactions.
Implementing Event-Driven and Asynchronous Patterns
Event-driven systems use message brokers like Kafka or RabbitMQ to communicate between services without blocking.
This asynchronous approach enhances reliability and helps fintech applications handle large-scale, real-time workloads.
Monitoring, Logging, and Observability
Monitoring should go beyond uptime.
Fintech developers need deep visibility into transaction performance, error rates, and customer behavior.
Tools like Prometheus and Grafana help visualize metrics, while ELK stacks capture detailed logs for compliance and troubleshooting.
DevOps Synergy: Continuous Integration and Deployment
Collaboration between development and operations (DevOps) ensures consistent, automated delivery.
With CI/CD pipelines, fintech teams can push frequent updates safely, a must for maintaining competitiveness.
DevOps and Microservices in Financial Services
DevOps practices in fintech go well beyond faster releases: they create systems that evolve without putting uptime or compliance at risk.
The Role of DevOps in Modern Fintech Infrastructure
DevOps practices enable smoother deployment workflows, better version control, and faster rollback when needed.
It’s the backbone of reliable fintech environments where downtime is unacceptable.
Infrastructure as Code (IaC) for Scalable Environments
Tools like Terraform or AWS CloudFormation let teams define infrastructure through code, making environments reproducible and auditable.
This reduces human error and accelerates scaling when demand spikes.
Testing Automation and Blue-Green Deployments
Automated testing ensures code changes don’t break critical payment paths.
Blue-green deployment strategies let fintech companies release updates to a small portion of users first, reducing disruption if something goes wrong.
Resilience Engineering: Chaos Testing and Failover Systems
Some fintechs intentionally simulate failures, a practice known as chaos testing, to ensure systems recover gracefully.
It’s a proactive way to validate resilience before real-world issues arise.
Security Integration: DevSecOps for Compliance-Ready Pipelines
Embedding security early in the development cycle helps meet compliance obligations without slowing delivery.
Static code analysis, dependency scanning, and policy-as-code tools all contribute to safer deployments.
Ensuring Compliance and Security in Microservices Architecture
Fintech systems handle sensitive data by definition, so every architectural choice must account for privacy and protection.
Handling Data Privacy (GDPR, PCI DSS, SOC 2)
Microservices should separate personally identifiable information (PII) and encrypt it both in transit and at rest.
Automated data classification tools help maintain compliance across distributed environments.
Beyond the architecture itself, you should have a solid understanding of what SOC 2, PCI DSS, KYC/AML, and DORA actually cost to run once engineering time is counted, not just the audit fee.
Secure APIs and Encryption
APIs are potential attack vectors.
Using rate limiting, OAuth 2.0, and TLS encryption keeps them safe while maintaining performance.
Access Controls, Auditing, and Role-Based Permissions
Each service should enforce strict access controls.
Role-based permissions and detailed audit logging make it easier to trace suspicious activities and prove compliance during audits.
Real-Time Fraud Detection and AML Integration
Microservices can enhance fraud detection by connecting transaction monitoring systems directly to AI-based analytics engines.
Suspicious transactions trigger alerts or freezes in real time, supporting AML and risk management initiatives.
Fraud detection system architecture breaks that pipeline into its five layers, from ingestion through case management, so the "AI-based analytics engine" is a specific, buildable component rather than a black box.
Future Trends in Microservices for Financial Services
Microservices are still evolving, and fintech is pushing their boundaries.
The Rise of Serverless and Function-as-a-Service (FaaS)
Serverless computing takes microservices further by letting developers deploy functions that scale automatically.
It’s cost-efficient for workloads that fluctuate, a natural fit for fintech companies processing unpredictable volumes.
Integration With AI/ML for Predictive Fintech Operations
Machine learning models embedded within microservices can detect anomalies, optimize lending decisions, or personalize user experiences dynamically.
AI-driven microservices could become the backbone of next-generation fintech innovation.
Composable Banking Platforms and Open API Ecosystems
Open banking and composable architectures are redefining how financial institutions collaborate.
Microservices make it easier to connect third-party APIs, create modular offerings, and stay flexible as new fintech ecosystems emerge.
One concrete example of that composability is embedded payments for SaaS platforms, where a software vendor exposes a payment capability as another API its customers consume rather than a bolted-on redirect to a third-party checkout.
Multi-Cloud and Hybrid Deployment Strategies
To avoid vendor lock-in and improve reliability, fintech teams increasingly distribute services across multiple clouds.
This approach supports resilience and compliance across jurisdictions.
Event-Streaming Architectures for Real-Time Analytics
Technologies like Apache Kafka and Pulsar power real-time data pipelines, letting fintech platforms analyze transactions and behavior instantly.
These event-streaming systems are becoming essential for fraud prevention and dynamic customer engagement.
Conclusion
Microservices architecture has reshaped how fintech organizations think about scalability, compliance, and innovation.
It breaks systems into manageable, secure, and flexible components, exactly what financial services need to handle complexity at speed.
With the right tools, culture, and partnerships, financial platforms can scale confidently while maintaining compliance, performance, and trust.
If you need a trusted tech partner who can help you hire specialist fintech developers, you are in the right place.
Request a consult to find out more about hiring with Trio!