

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Cross-border payments still lag domestic ones: transfers can take days, and fees average around 6-7 percent on remittances.
- The biggest structural shift is the direct interlinking of domestic instant-payment systems across borders, through projects like BIS Project Nexus and Africa’s PAPSS.
- ISO 20022 provides richer, structured data that reduces errors, improves compliance, and lets systems actually talk to each other.
- Stablecoins, tokenized deposits, and CBDCs are emerging as alternative settlement rails that can bypass correspondent banking.
- The hard parts are interoperability, fragmented regulation and AML, and fraud.
Cross-border payments fund trade, support families through remittances, and connect digital marketplaces that span continents.
But despite the trillions that move each year, the system behind those transactions still feels slow, expensive, and oddly opaque.
Transfers can take days to settle, fee structures are sometimes unclear, and liquidity can get stuck in the wrong place at the wrong time.
The problem is that users expect to be able to send money almost instantly, so banks, fintechs, and central banks are now working to close the gap between expectation and reality.
Let’s take a closer look at the fintech industry’s focus on instant payment systems, better data standards, and smarter liquidity management, all in an effort to make cross-border instant payments faster, cheaper, and far more transparent.
Our fintech developers here at Trio help people take advantage of those opportunities by providing all the skills and production experience you need from the get-go.
The State of Cross-Border Payments
Cross-border payments are becoming more popular in modern finance, especially as remote work becomes more popular, but the machinery that supports them still carries the weight of decades-old infrastructure.
Definition of Cross-Border Payments
A cross-border payment happens whenever the payer and the recipient are based in different countries.
Behind the scenes, this sets off a web of payment systems, financial institutions, and correspondent banks, who all need to work together to handle the routing, currency exchange, and compliance checks that make the transfer possible.
Importance in Global Trade, Remittances, and Financial Inclusion
These payments matter for large institutions, but also for small exporters, families sending remittances, and even gig workers paid through global platforms.
The World Bank estimates that personal remittances reached about $685 billion to low- and middle-income countries in 2024, and have kept climbing since.
The problem is that the average fee for sending money internationally still averages around 6.5% globally in 2025, which is far above the 3% target, and just makes it too expensive for some to consider.
Market Size and Growth Outlook
Total cross-border payment flows reached reached well over $150 trillion in recent years and are projected to exceed $250 trillion by 2027, according to the Financial Stability Board.
We’re seeing a lot of this growth coming from B2B, e-commerce, and SME trade, especially across Asia and Africa.
Estimates of the cross-border payments market (the revenue layer, not total flows) vary widely by source, but some are even projecting it will roughly double over the next decade.
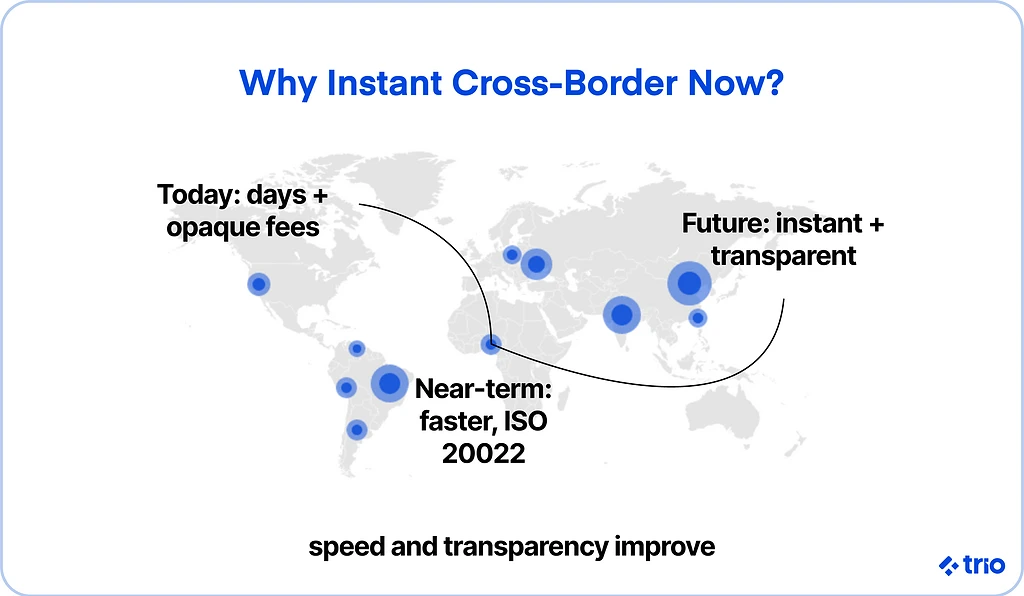
As more markets adopt ISO 20022 messaging and real-time payment rails, some of the old frictions will start to fade. But this will only happen if the different systems can actually talk to each other.
The Rise of Instant Payments in Cross-Border Transactions
Speed has always been the weak link in international transfers. Domestic payments are often instant, while international ones can take several days.
What Are Instant Payments?
Instant payments, sometimes called real-time payments, allow money to move and settle within seconds, all day, every day.
Extending that experience across borders is incredibly difficult.
As you can imagine, different rules, currencies, and time zones can complicate things.
Benefits of Cross-Border Instant Payments
Our experience working with fintechs that build and scale payment infrastructure has shown us how real-time systems reshape the way liquidity is handled, particularly in regulated markets where compliance and uptime both matter.
For businesses, faster settlement is essential because it can free up working capital and smooth out cash flow.
For individuals, it means remittances arrive when they’re needed most.
And for financial institutions, instant payments make it possible to reconcile transactions in real time, lowering operational risk.
Challenges in Implementing Instant Payments
Interoperability is the sticking point here, since every country runs its own systems and enforces its own rules.
The G20 roadmap led by the Financial Stability Board (FSB) and the Committee on Payments and Market Infrastructures (CPMI) under the Bank for International Settlements aims to set measurable improvements in speed, cost, and transparency by 2027.
But coordination across dozens of regulators and systems has never moved quickly in the past, so we’re not expecting it to do so in the near future.
Key Trends Shaping the Cross-Border Payments Landscape
The cross-border payments market is evolving, but not in a single direction. Technology, policy, and private-sector innovation are pulling at it from different angles.
Here are the five trends defining 2026.
Trend 1: Faster Payments and the Interlinking Modernization of Payment Rails
Governments and central banks are upgrading the pipes. Europe’s TARGET Instant Payment Settlement (TIPS) and the U.S. FedNow network, for example, mark real progress toward faster cross-border payments.
The far bigger shift is direct interlinking of these domestic instant systems across borders.
- The BIS-backed Project Nexus is moving toward live implementation, connecting the national instant-payment systems of its five founding members (India, Malaysia, the Philippines, Singapore, and Thailand) through a single gateway, with go-live targeted for around 2026 to 2027
- Africa’s Pan-African Payment and Settlement System (PAPSS) is also expanding intra-African trade by settling in local currencies.
- Singapore’s PayNow linked to India’s UPI is an early live example of what this looks like in practice.
Trend 2: AI, Data, and Automation in Payments Processing
Many financial institutions are now using AI for compliance checks, fraud detection, and reconciliation.
The change is playing a massive role in facilitating speed and reliability at scale.
Payments that once required manual review now clear in seconds, with fewer errors, taking care of one of the primary blockers of instant payments.
Trend 3: Stablecoins, Blockchain, Digital Assets, and Tokenized Liquidity
Stablecoins have made the news a lot in recent years because they settle on a shared ledger in near real time. This allows them to bypass slow correspondent-banking chains, offer close-to-instant FX, and cut intermediary fees, which is why they now feature prominently in how the market and search engines describe cross-border trends.
Regulation is catching up as well, with US stablecoin rulemaking under the GENIUS Act being one example of the guardrails forming around payment stablecoins.
Several central banks are also exploring central bank digital currencies (CBDCs) or tokenized deposits to improve settlement efficiency.
Projects like BIS’s mBridge appear to demonstrate how tokenized liquidity could streamline wholesale cross-border transactions, though questions around governance and privacy remain open.
Trend 4: Embedded Finance and Emerging Retail Corridors
Embedded payment infrastructure changes the economics of scaling across markets.
For the average company, it’s less about launching new rails and more about connecting the right ones.
In fast-growing regions, embedded payment solutions are enabling SMEs to trade across borders with minimal friction.
Trend 5: Cybersecurity, Fraud Prevention, and Resiliency
As we’ve already alluded to, one of the primary issues institutions are encountering is that, as instant systems scale, they invite new forms of attack.
The industry is responding with real-time fraud analytics and stronger authentication protocols, but full resilience requires ongoing cooperation between providers, regulators, and users.
Banking and Liquidity Management in Cross-Border Transactions
The core challenge has always been how to keep money flowing across borders without locking up too much capital.
The Role of Banks and Correspondent Networks
Correspondent banking is still the backbone of global transfers. These relationships allow banks to settle in multiple currencies and jurisdictions.
However, it looks like the network has been shrinking, with the number of active correspondent banks down by around a fifth over the past decade and still falling, according to the BIS, as compliance costs rise.
Liquidity Management for Real-Time Cross-Border Flows
Real-time settlement forces a rethink of liquidity management. Banks are investing in automated tools that forecast balances and trigger intraday funding.
Systems like SEPA Instant Credit and TIPS show how shared liquidity pools can maintain speed without excessive pre-funding.
One important factor here is that SEPA Instant’s phased mandate is now in effect across the euro area, which has pushed adoption sharply.
Central Bank Initiatives and CBDC Pilots
We’ve already mentioned how many central banks are now testing CBDCs for cross-border use.
Several major central banks, including those in Europe, the UK, and Singapore, have explored how interoperable CBDCs might enable more direct settlement between institutions.
It’s still very early, though, and technical and legal hurdles continue to slow broad adoption.
How Fintech Partnerships Are Transforming Liquidity Models
Fintechs and banks are experimenting with joint liquidity tools, API-driven dashboards, automated sweeps, and cross-currency matching engines.
These collaborations are reshaping the economics of settlement, but they depend heavily on shared standards and trust, which are clearly going to be essential moving forward.
Regional Perspectives on Cross-Border Payments
No two regions are modernizing in quite the same way. Regulation, market maturity, and infrastructure all influence what instant actually means, and if you are going to operate in more than one area, you will need to be prepared to deal with this variation.
Europe: SEPA Instant and ECB Initiatives
Europe’s Single Euro Payments Area (SEPA) and TARGET Instant Payment Settlement programs have created a unified space for instant payments in euros.
The European Central Bank is still pushing for full adoption
The SEPA Instant Payments Regulation has also required euro-area providers to receive instant payments since January 2025 and to send them since October 2025, but smaller institutions are still catching up.
United States: FedNow, RTP, and Cross-Border Expansion
The launch of FedNow in 2023 added momentum to U.S. modernization efforts. Combined with The Clearing House’s RTP network, it could open the door to international linkages that make international payment processing more predictable.
Asia-Pacific: Singapore, India, and China as Innovation Hubs
There is a lot of variation happening in the Asia-Pacific region.
Singapore’s PayNow-FAST linkage with India’s UPI lets users send money directly between accounts in seconds.
China’s cross-border e-CNY pilots also point toward practical CBDC use.
For now, it almost seems like Asia is setting the pace globally.
Latin America and Africa: Mobile-First Corridors and Remittance Growth
In Latin America and Africa, mobile-first ecosystems like Pix and M-Pesa are expanding retail cross-border payments.
These systems may not always meet the technical definition of instant, but they’ve drastically reduced remittance costs and increased access for unbanked users, and in some cases created some of the region’s largest unicorns.
Africa’s PAPSS, which we mentioned above, is now the regional layer connecting many of these systems for cross-border settlement.
Challenges and Risks in Cross-Border Payments
Progress hasn’t removed complexity. In some ways, faster systems expose how fragmented the global regulatory landscape still is.
We have already mentioned many of these challenges and risks in passing, but it is worth stating each one explicitly.
Regulatory and Compliance Hurdles
Licensing, AML rules, and data protection laws differ from country to country, which makes scaling cross-border services slow and expensive.
From what we’ve seen, it’s safe to say that global alignment is unlikely for a while longer, but there’s growing pressure for baseline standards that at least make compliance less redundant.
Anti-Money Laundering and Counter-Terrorism Financing Obligations
Stronger oversight is going to be non-negotiable, but stricter controls can delay legitimate transfers.
Shared KYC databases or digital ID frameworks might help, though privacy concerns often limit how much information can actually be exchanged.
Transparency Issues and Hidden Fees
Hidden FX spreads and unclear charges still frustrate users.
Initiatives from the Financial Stability Board and the Bank for International Settlements focus on promoting transparent cross-border payments.
The big issue here is that the market’s incentive structure, where intermediaries profit from opacity, makes reform slow.
The Decline of Correspondent Banking Relationships
Fewer correspondent banks mean fewer corridors, and small economies are often hit hardest, losing access to affordable settlement routes.
Restoring coverage may depend on shared digital infrastructure rather than rebuilding old bilateral relationships.
The Future of Cross-Border Payments
The next decade may see the boundaries between domestic and international payments blur entirely. There are a couple of trends we are following that could prove promising.
The Convergence of Instant Payments, CBDCs, and Blockchain
CBDC projects and blockchain-based settlement layers are starting to overlap.
If these systems can connect reliably, cross-border payments could clear in seconds, not days.
That said, interoperability is harder to achieve than to promise, and it may take years before pilots turn into production networks.
The Impact of Open Banking and Interoperability Standards
Open banking APIs are creating new pathways for payments. Combined with ISO 20022 data, they allow financial institutions to plug directly into each other’s systems rather than rely on messaging chains.
Early results suggest fewer errors and fewer intermediaries.
How Retail Payment Trends Are Reshaping Cross-Border Adoption
Consumer behavior is always going to be one of the primary factors pushing the industry forward.
Shoppers expect seamless checkouts and instant refunds. Businesses that can’t deliver that level of experience across borders risk losing trust fast.
Predictions: Faster, Cheaper, and More Inclusive
If current projects stay on track, we can only assume that global cross-border payments will likely become faster, cheaper, and more inclusive by the end of the decade.
But technology alone won’t guarantee fairness or access.
The reality is that policy choices, interoperability, and governance will decide whether the benefits reach everyone, or just the most profitable corridors.
Strategic Recommendations
Different players in the ecosystem face very different challenges, but a few principles hold across the board.
For Banks: Modernize Infrastructure and Embrace Partnerships
Banks need to keep modernizing legacy systems and adopt API connectivity where possible. Partnering with fintechs often shortens the path to efficient cross-border payments and gives access to faster innovation cycles.
For Fintechs: Leverage Compliance and Liquidity Innovation
Fintechs that understand regulation as well as code will scale faster. Tools that improve liquidity visibility and automate compliance can turn what used to be a cost center into a competitive edge. Consider what you can provide to others, but also what others are already providing that you may be able to use in your own products.
For Regulators: Foster Interoperability and Transparency
Collaboration between regulators is improving, but gaps remain. Shared data frameworks and consistent payment systems standards could enhance cross-border payments without compromising national oversight. The world needs to adapt to changing risks, so regulators are going to need to be quick to adapt, and communication could make that a lot easier on a global scale.
Conclusion
The cross-border payments market is changing direction, but the transition will take time.
At the moment, we are dealing with systems built for a slower world, but these are gradually being replaced with more modern infrastructure.
Alignment between banks, fintechs, and central banks is going to be essential.
Our developers have the niche experience required to help teams build financial systems that move as quickly as the markets they serve.
To hire fintech developers with Trio, request a consult.