

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Scalable technology solutions in fintech need to handle compliance, audit requirements, and data integrity at scale simultaneously, which changes the architecture significantly compared to general software scalability.
- Microservices buy the ability to scale one service at a time- a payment gateway under peak load, for example- without redeploying the rest. The pattern is common in fintech rather than universal: modular monoliths still run plenty of regulated platforms at volume.
- Cloud infrastructure from AWS, GCP, or Azure supplies the elastic capacity, but fintech adoption runs into cross-border transfer restrictions, PCI DSS scope, and the third-party ICT risk obligations DORA has placed on EU financial entities since January 2025.
- Event-driven architecture using tools like Apache Kafka appears consistently in scalable fintech platforms because financial systems need to process and react to transactions in real time without creating bottlenecks.
- The most expensive scalability problems show up during migration, when one team keeps the old system running while another builds its replacement.
- Scaling a fintech team requires the same thoughtfulness as scaling the technology. Engineers who haven’t worked in regulated financial environments tend to underestimate the compliance surface of every architectural decision.
Whether you’re an established fintech company grappling with the challenges of expansion or a startup preparing for rapid growth, finding the right scalable technology approach tends to determine whether that growth goes smoothly or turns into a firefighting exercise.
The difference between a fintech platform that scales confidently and one that buckles under pressure usually comes down to architectural decisions made early, often before the growth pressure was visible, that either compound in your favor or work against you at the worst possible moment.
At Trio, we’ve helped fintech teams across payments, lending, and digital banking work through these decisions.
This guide covers what scalable technology actually means in a fintech context, why the stakes are higher in regulated financial environments than in most other software domains, and what the architecture actually needs to look like if you want to scale without rebuilding everything twice.
If you are interested in hiring Trio’s expert fintech developers, pre-vetted so that they can be placed in as little as 3-5 days, view capabilities.
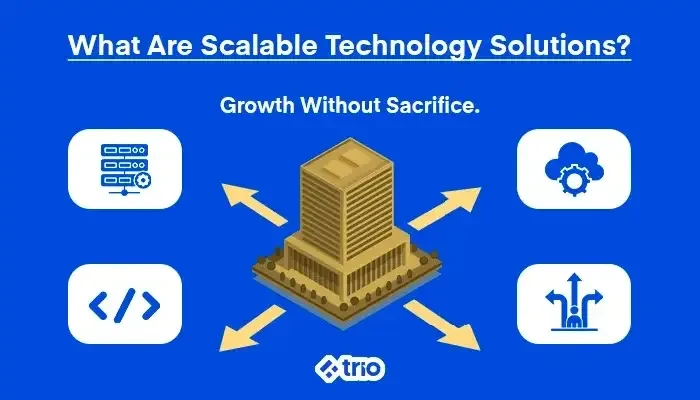
What Scalable Technology Solutions Actually Mean
Scalable technology solutions are the systems, frameworks, and tools that grow alongside a business without sacrificing performance, security, or compliance.
For general software businesses, scalability typically means handling more users and more data without the system slowing down or crashing.
Two mechanics sit underneath that.
Vertical scaling adds capacity to one machine, quick to do and simple to reason about, until the largest instance available runs out. Horizontal scaling spreads load across more machines, which costs engineering effort up front and removes the ceiling, and it tends to be the one that matters once transaction volume grows unpredictably.
However, if you are working in the fintech industry, then scalability also involves handling more transactions, more users, and more data while maintaining the accuracy, auditability, and compliance posture that financial systems require.
A payment platform that processes 10,000 transactions a day and one that processes 10 million need fundamentally different architectures, but both need every transaction to reconcile correctly, every piece of customer data handled according to applicable regulations, and every system failure recovered without data loss or duplication.
That is why the architecture choices matter more in fintech than they do in less regulated domains.
Why Scalability Breaks Down in Fintech (and When)
A team that builds a financial product quickly often builds on a monolithic architecture because it’s faster to ship, and it works well at an early scale.
The problem is that, as growth accelerates, issues can start to arise.
Transaction processing slows during peak periods because the entire system competes for the same resources, and even a small feature update to one part of the product requires redeploying everything, introducing risk across the system for a small change.
Fixing anything under growth pressure costs significantly more than designing around it from the start.
You will need to migrate, sometimes over several months, without breaking your live application.
And, during this time, your team is split between maintaining the old system and building the new one. Teams that started with modular design don’t face that choice.
Designing for modularity early costs far less than splitting a system later under load.
The Architecture of Scalable Fintech Technology
Several architectural patterns appear consistently across fintech platforms built to scale.
Microservices Architecture
Microservices break down a financial application into smaller, independent services, each responsible for a specific domain.
Instead of one monolithic system handling payments, user authentication, KYC checks, reporting, and notifications, each of those functions runs as a separate service that communicates with the others through APIs.
This approach gives your teams the ability to scale individual services independently.
For example, if a payment gateway experiences a traffic spike, teams can scale just that service without touching the rest of the system. If a notification service fails, it doesn’t take down the entire platform.
For fintech specifically, microservices also make compliance management more tractable.
PCI DSS scope reduction becomes possible when the cardholder data environment is isolated in dedicated services rather than spread across a monolith.
The tradeoff is complexity.
Microservices introduce distributed system challenges, inter-service communication overhead, and observability requirements that a monolith doesn’t have.
If you are going to use microservices, then your teams need the engineering discipline to define service boundaries correctly, manage API versioning, and handle partial failures gracefully.
Cloud Infrastructure and Elastic Scaling
Cloud platforms like AWS, Azure, and GCP provide fintech companies with the infrastructure to handle spikes in user activity or transaction volume without building and maintaining dedicated hardware.
The elastic scaling these platforms offer, automatically increasing or decreasing compute resources based on demand, directly addresses things like transaction volumes that are predictable on average but highly variable at peak.
Payment systems experience predictable spikes (payroll days, tax periods, Black Friday for payment processors), and cloud infrastructure can handle those spikes without the system degrading.
If you used an alternative that did not allow for elastic scaling, you would have to choose between overprovisioning hardware that sits idle most of the time or underprovisioning and accepting degraded performance during peaks.
Cloud adoption in fintech still demands more careful architecture than general software does.
Data residency requirements, PCI DSS compliance, and regulatory frameworks like DORA in the EU create constraints on where data can be stored and processed, how access is controlled, and what security standards apply to cloud infrastructure.
You need to make sure you get your architecture right upfront. This may be expensive, but in our experience, it costs a lot less than the remediation work that follows a compliance finding or a data residency violation discovered post-launch.
Event-Driven Architecture
Event-driven architecture, often built on tools like Apache Kafka or AWS EventBridge, processes financial events in real time by decoupling the services that produce events (a payment being initiated) from the services that consume them (fraud detection, ledger updates, notification triggers, analytics).
That matters because transactions need to be processed quickly and propagated accurately across multiple systems simultaneously. A payment that completes needs to update the ledger, trigger a fraud check, send a notification, and feed into analytics, often within milliseconds.
Event-driven architecture lets all of those processes happen in parallel without each depending on the others completing first, so they happen faster overall.
This modularity is also the foundation of a resilient fintech backend. If the notification service fails, the payment still processes and the ledger still updates. The failure is isolated rather than cascading.
As an added benefit, event-driven architecture also provides a natural audit trail, since every financial event can be logged and replayed, which matters for compliance and for debugging reconciliation discrepancies.
API-First Design
An API-first approach designs financial services so every function is accessible through a well-defined API from the start.
The reason this is often better than adding APIs as an afterthought is that you ensure that every service is modular, reusable, and easily integrated with partners, which matters particularly in an era of Open Banking and embedded finance.
For fintech companies building on Banking-as-a-Service (BaaS) infrastructure or participating in open banking ecosystems, API-first design is the mechanism through which your platform connects to the broader financial infrastructure it depends on and the partners it serves.
API versioning, rate limiting, throttling, and per-tenant access policies all become important architectural considerations when external parties depend on your APIs.
Containerization and Orchestration
Docker and Kubernetes have become standard tools for deploying scalable fintech infrastructure.
Containers package application code with its dependencies in a portable, consistent unit that runs identically across development, staging, and production environments.
Kubernetes then orchestrates those containers, handling automated deployment, scaling, and recovery.
If you use continuous deployment, containerization supports fast and reliable releases and can help document change management for compliance frameworks like SOC 2 and PCI DSS.
A CI/CD pipeline that runs automated tests, builds a container image, and deploys through Kubernetes produces the change evidence SOC 2 Type II controls and PCI DSS Requirement 6.5.1 expect: the reason for a change, its security impact, documented approval, and a route back to a secure state.
Requirement 6.3.2 asks for something different: an inventory of your bespoke software and the third-party components inside it, which the same build step can emit as a software bill of materials.
Scalability and Compliance: Why They Can’t Be Separated in Fintech
Compliance requirements like PCI DSS, GDPR, and SOC 2 need to be incorporated into your scalability considerations from the start, with sensitive data tagged and secured appropriately at the architecture level.
Retrofitting compliance onto a scaled system that wasn’t designed for it typically costs far more than building it in, and it is incredibly difficult for developers to do so without affecting the rest of the application.
A few specific intersections matter most:
PCI DSS scope management: Every service, system, and network component that touches cardholder data falls within the PCI DSS scope. In a microservices architecture, the PCI scope can be contained to specific services.
Cross-border transfers and GDPR: GDPR sets no general data residency rule. It restricts moving personal data outside the EEA without an adequacy decision or another Chapter V safeguard, which pushes many fintechs toward EU cloud regions anyway. DORA adds third-party ICT risk obligations that reach cloud providers and other critical vendors, so a multi-region design has to satisfy both.
Audit trails at scale: Regulators expect financial institutions to produce accurate, complete audit trails of financial events. At scale, generating and retaining those audit trails requires deliberate architectural support. Event-driven architectures with append-only event logs provide this naturally.
Idempotency in payment systems: Payment systems that can’t guarantee idempotency create reconciliation discrepancies that grow in severity as transaction volumes increase. Designing idempotency correctly in payment APIs is an architectural decision.
Building Scalable Fintech Products: Best Practices
In our experience, the engineering practices that separate fintech platforms built to scale from those that hit ceilings tend to cluster around a few consistent themes.
Design for failure from the start: Designing fault-tolerant systems that handle failure modes gracefully, with retry logic, idempotency keys, and compensating transactions, requires treating failure as a design input rather than an edge case.
Instrument everything: Distributed tracing, structured logging, and real-time metrics (Prometheus, Grafana, Datadog) provide the observability needed to identify performance bottlenecks, track transaction flows across services, and detect anomalies before they become incidents.
Separate read and write paths: Financial systems frequently have very different read and write patterns. Command Query Responsibility Segregation (CQRS) patterns and read replicas are common solutions for fintech platforms that need both without degrading the other.
Plan data migrations before you need them: Schema changes to financial databases at scale are risky. Teams that think about database evolution strategies (blue-green deployments, expand-contract migrations, feature flags to control rollout) before they face a migration under pressure do it more safely and quickly.
Automate compliance testing: New regulations emerge, existing standards are updated, and the interpretation of requirements evolves. Fintech teams that have automated compliance testing as part of their CI/CD pipeline catch regressions before deployment rather than discovering them during an audit.
Related Reading: What is a Forward Deployed Engineer in Fintech?
When Building for Scale Is the Wrong Call
Scaling work costs something, and most of that cost lands before any traffic arrives. A team that splits a product into eight services before it knows which parts change together pays the coordination bill without collecting the independence.
A few situations where the patterns above tend to do more harm than good:
Products still searching for fit, where service boundaries get redrawn every quarter. A modular monolith with clean internal interfaces keeps most of the later flexibility at a fraction of the operational cost.
Small teams. Running Kubernetes, a message bus, and distributed tracing takes people, and below roughly ten engineers, that infrastructure competes with the roadmap instead of supporting it.
Workloads that stay small. A lending back office handling a few thousand applications a month will never feel the difference, and the audit story stays simpler in one deployable.
Postings that must commit atomically. Spreading a ledger write across services means sagas and compensating transactions, which work, but they introduce failure modes a single database transaction does not have.
Event-driven designs carry their own bill. Once events become the contract between services, you inherit ordering, replay, and schema evolution problems, and tracing a reconciliation gap means reading a stream of events rather than a row in a table.
None of this argues for ignoring scale. It argues for matching the architecture to the load and the regulatory surface you actually have, then revisiting that choice when either one moves.
How Trio Helps Fintech Teams Scale
Building scalable fintech technology requires engineers who understand both the technical patterns and the financial systems context those patterns need to serve.
Trio’s developers have production experience building and maintaining financial systems at scale, including payment processors, lending platforms, and digital banking infrastructure.
We pre-vet developers, so they can be placed as soon as we have a thorough understanding of your project requirements. This can be as little as 3-5 days after our initial meeting.
If you want these senior fintech experts on your team to ensure you build scalable technology solutions, request a consult.