

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Issuing a card puts you in the authorization path, which means policy becomes something enforced before any money moves.
- Card-first, travel-first, procurement-led, AP-led, and modular/global architectural archetypes each solve a genuinely different engineering problem, and most major platforms span more than one.
- ERP integration can consume a large share of engineering effort.
- Agentic shifts have moved several platforms from suggesting actions to taking them, including posting journal entries and resolving support chats autonomously, which changes the engineering requirement from modeling to governance.
Spend management consolidated hard in 2026, with Capital One acquiring Brex for $5.15 billion and Ramp reaching a $44 billion valuation.
However, underneath the market noise, the category’s defining engineering bet has stayed constant. People want to move control from after-the-fact reporting to enforcement at the authorization moment itself.
Let’s take a look at everything you need to know about US spend management platforms in 2026, including the five archetypes on the market.
To develop or integrate your own spend management platforms, you are going to need expert development talent with production experience in the fintech industry.
That is exactly the kind of talent we provide at Trio; whether you need access through IT staff augmentation or you want a fintech software development company to outsource the entire process to, we can assist.
What Changed in 2026
A lot has happened in 2026 that has had an effect on US spend management platforms.
Capital One started the year strong when they agreed to acquire Brex for $5.15 billion in January 2026, with the deal closing April 7, 2026.
That followed Capital One’s earlier Discover merger, which means that a single institution now holds a payments network, a large commercial card portfolio, and an AI-native spend platform.
Ramp, on the other hand, raised a $750 million Series F in June 2026 at a $44 billion valuation, led by ICONIQ, GIC, and Ontario Teachers’ Pension Plan, with annualized revenue reaching roughly $1.5 billion by that point.
If we look at the entire market, the AI-native spend and finance automation segment was valued somewhere in the high single-digit billions in 2025, with some predicting a double-digit percentage CAGR through the early 2030s.
Structurally, it seems there are two important things happening at once.
First, the entire spend management category is consolidating into incumbents: a bank, two HR platforms, and SAP.
The remaining independents raised at valuations that assume they become the finance operating system rather than staying a card product.
The Category’s Defining Engineering Bet
Legacy expense management is, for the most part, just a reporting system.
It tells you that someone spent money and submitted a receipt, but you only really find out afterwards, so reconciling, categorizing, and enforcing policy can only happen retrospectively.
More modern solutions understand that the moment you issue the card, you sit inside the authorization path, and policy becomes something you enforce before the money moves rather than something you report on after the fact.
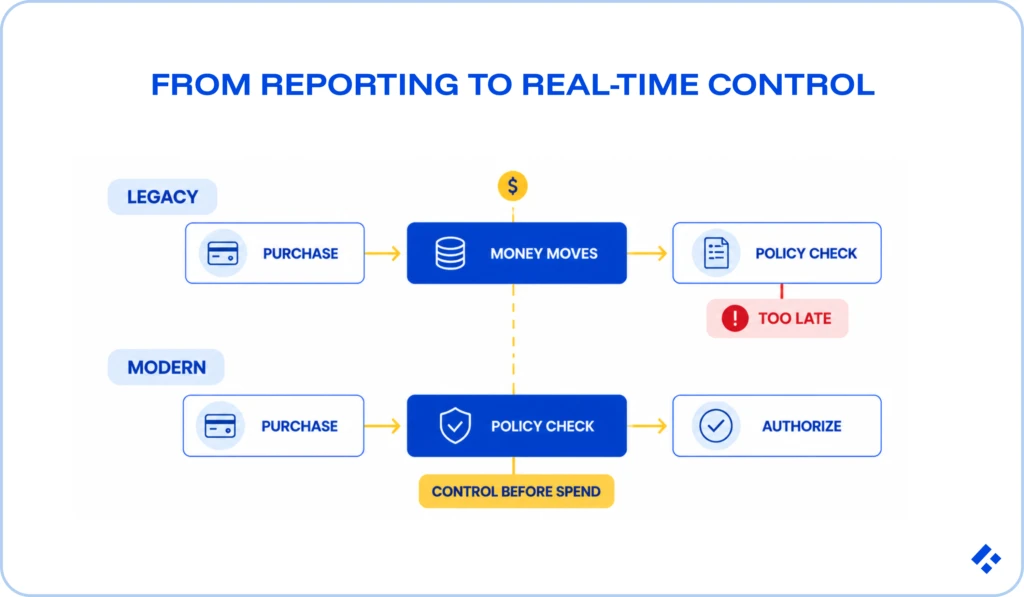
When you are working with people’s money, authorization decisions are real-time and unforgiving. A card network authorization carries a hard latency budget measured in a few hundred milliseconds, and your policy engine, your ledger balance check, your risk model, and your merchant-category logic all have to resolve inside that window.
The policy engine sits directly in the money path too, so any bug here can decline a legitimate purchase at checkout or, arguably worse, approve one that breaches a control.
State also has to be correct at the exact moment of decision. That means that things like available balance, budget remaining, and vendor status all have to be current at authorization time.
Five Archetypes: Five Different Problems
| Archetype | Examples | Core engineering problem | Where it struggles |
| Card-first | Ramp, Brex, BILL Spend & Expense | Real-time authorization and policy enforcement; underwriting | Procurement depth, POs, three-way match |
| Travel-first | Navan, SAP Concur | Inventory and booking integration; itinerary-to-expense linkage | Non-travel spend categories |
| Procurement-led | Coupa, Zip, Procurify | Approval workflow, supplier management, three-way match | Getting ahead of card spend |
| AP-led | BILL, Stampli | Invoice capture, matching, payment orchestration | Employee spend at point of purchase |
| Modular/global | Payhawk, Brex (post-acquisition) | Multi-entity, multi-currency, per-jurisdiction compliance | Depth versus breadth per module |
Card-first platforms build issuing infrastructure (either their own BIN or a partner’s) alongside real-time authorization and a real credit decision.
Travel-first platforms treat booking integration as its own distinct discipline, with GDS and supplier connections, inventory management, cancellation and change semantics that don’t map cleanly onto a simple transaction.
Procurement-led platforms live inside workflow engines, supplier master data, and three-way match logic.
AP-led platforms do document capture and matching at real scale, and typically involve OCR, line-item extraction, and reconciling against purchase orders and receipts.
Modular and global platforms take on what is arguably the hardest problem of the five. Multi-entity, multi-currency, per-country tax and card scheme rules mean every new jurisdiction is a new compliance surface.
The problem every single archetype shares regardless of category is ERP integration, which is usually where a large share of engineering time ends up going.
The Four Problems Everyone in This Category Is Solving
- The ledger: Multi-entity balances, real-time available-to-spend calculations, holds and releases between authorization and eventual settlement, and a record that reconciles to the customer’s own general ledger.
- Reconciliation: Card transaction to receipt to GL entry, at real volume, across settlement timing that frequently doesn’t match the original authorization time at all.
- Categorization and enrichment: Merchant data coming from card networks can have truncated names, wrong merchant category codes, and aggregator strings that mean nothing on their own. Turning that into a usable vendor and category requires an enrichment pipeline plus a model.
- Policy modeling: Every customer’s spend policy is different, and expressing that as rules evaluable inside a tight authorization latency budget, without a per-customer code branch multiplying forever, is difficult.
The Agentic Shift, and What It Requires
Ramp launched Stack in June 2026. It’s an AI operating system for accounting firms, built on agents Ramp calls “Coworkers,” which can assist in handling reconciliations, journal entries, transaction coding, and variance analysis across a firm’s entire client book.
But that’s just one example of an agentic shift that has been happening for quite some time.
In terms of engineering, having AI actually complete tasks as opposed to simply suggesting them is a different risk profile completely. The difficult part, likewise, shifts from the model to the guardrails built around it.
Reversibility is becoming critical, since every autonomous action needs a defined undo path and an audit record of exactly what the agent did and why.
You will need confidence thresholds and escalation, a defined boundary where the agent stops and hands off to a human, tuned per action type rather than set globally across the whole system.
Regulators are also expecting explainability, captured and stored at the actual moment of action.
What This Means If You’re Building Here
The card-first position is probably the most expensive to attack head-on.
Most incumbents already have issuing infrastructure, underwriting data, and free entry-level pricing. The more realistic openings sit in vertical depth and geography.
If you’re already inside a platform, the newer pressure is agent governance specifically, and the teams that shipped agentic features fastest are now discovering the audit and reversibility requirements they’d deferred while racing to ship.
Realistically, you are going to need payments engineers who understand authorization and settlement semantics, integration engineers who can survive a real NetSuite implementation, and, increasingly, people who can put real governance around an agent that touches a ledger directly.
At Trio, we provide exactly these kinds of people, with several years of guaranteed production experience in similar projects.