

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Revenue share and spread ownership are different businesses. The provider takes its cut either way, around 20 to 30 basis points, where rates are published. Whether you keep the rest decides whether payments become real revenue.
- Take rates climb sharply as platforms mature, from a 53bps median for platforms early in their payments journey to a 98bps median for scaling and optimized ones.
- Registration ownership and loss responsibility are separate questions. The provider usually holds the registration, while reserves, indemnities, and dispute-rate thresholds can still push merchant losses back to you. Ask both questions separately.
- Flat-rate pricing is fine for small volumes but gets expensive at scale. Finix puts the annual gap against interchange-plus at roughly $12,000 at $50,000 a month in card volume and over $24,000 at $100,000. Finix sells interchange-plus, so read it as a direction.
- Integration runs from a few days to several months depending on the model.
Payment facilitation used to mean picking up a registration, a sponsor bank, an underwriting function, and a compliance team, then waiting a year.
These days, however, payfac-as-a-service providers have compressed that into an integration.
The catch is that the label covers arrangements that differ enormously.
Two providers both selling “payfac-as-a-service” can leave you with completely different economics, completely different liability, and a go-live date six months apart.
Let’s look at ten payfac-as-a-service providers, and compare them on the things that actually vary.
At Trio, we have a pre-vetted pool of fintech specialists who are already familiar with the industry. These software developers can draw on their production experience to help you identify the right vendor for your product and can assist with the integration.
10 PayFac-as-a-Service providers compared
Provider | Model | Economics | Typical go-live | Geography |
Stripe Connect | Platform-managed, configurable | Flat rate plus Connect fees | 1-3 weeks (Express), 4-12 weeks (Custom) | 46+ countries, 135+ currencies |
Adyen for Platforms | Enterprise PFaaS | Interchange-plus, spread ownership | 2-4 months | Global |
Finix | PFaaS with path to full payfac | Wholesale rates, you set pricing | Weeks to months | US, Canada |
Worldpay for Platforms | Three tiers incl. PayFac Developer | Negotiated, revenue share or spread | Months | Global |
Rainforest | Purpose-built PFaaS | Interchange-plus buy rate, revenue split on spread | 2-6 weeks | US (Canada planned) |
Tilled | PFaaS, published pricing | Revenue share, no platform fees | Weeks | US, Canada |
Infinicept | Enablement plus managed option | Spread above cost | Weeks (Launchpay), 3-4 months (full) | US-focused |
Payabli | Developer-first PFaaS | Negotiated | Days to weeks (no-code) | US |
Stax Connect | Managed PFaaS | Custom | Weeks to months | US |
Payroc | PFaaS with registration path | Negotiated, aggressive on buy rate | Weeks to months | US, Canada, UK |
Stripe Connect
This is usually the default starting point, and there are many reasons why.
Documentation is excellent; the embeddable components do most of the onboarding work, and you can be processing quickly.
Shopify and DoorDash both run on Stripe Connect, proving that it can be used successfully.
The trade-off sits in the economics.
Flat-rate pricing at 2.9% plus 30 cents is predictable and generous at low volume, but it can very quickly become one of the most expensive options as you scale.
Finix publishes a comparison putting the annual gap against interchange-plus at roughly $12,000 at $50,000 a month in card volume, and over $24,000 at $100,000 a month. Finix sells interchange-plus, so read those as a direction rather than a quote.
For international coverage, though, nothing on this list competes.
Adyen for Platforms
Adyen is one of the best enterprise options, with genuine global acquiring and depth in card-present alongside online.
You benefit from spread ownership rather than revenue share, so the economics work in your favor at scale.
The main issue here is that it expects more of you.
Integration runs for months, and Adyen’s commercial process assumes a platform with real volume already.
Adyen confirms it charges a minimum invoice that varies by industry and business model, without publishing the amount. Third-party estimates put the practical floor somewhere around $150,000 to $200,000 a month, below which this is usually more platform than the problem requires.
Finix
With Finix, you can start on payfac-as-a-service and migrate to full payfac registration later without changing providers.
For a platform that expects to own its payments eventually, that removes a painful migration from the roadmap.
Developer experience is strong, wholesale rates are negotiable, and you set sub-merchant pricing.
Finix also accepts higher-risk verticals that some competitors may decline.
Worldpay for Platforms
Payrix was folded into Worldpay for Platforms, which now operates under the Global Payments for Platforms brand following Global Payments’ completed acquisition of Worldpay on 12 January 2026 in a deal reported at around $24.25 billion.
The product runs three tiers: Integrated Payments, PayFac-as-a-Service, and PayFac Developer.
This variety means you can choose how much underwriting and compliance risk to carry.
The platform offers enterprise depth, omnichannel coverage, and serious risk tooling. Implementation timelines reflect that.
Rainforest
Rainforest was built specifically for vertical SaaS, and it publishes its buy rates: 30 basis points below $5 million a month, 25 between $5 and $15 million, 20 above that. There is no revenue split, so whatever you charge above cost is yours.
Go-live takes roughly two to six weeks through a single API with pre-built components.
The platform’s services are currently offered only in the US, with Canada expansion planned, which rules it out for international platforms today.
For a US vertical SaaS business that wants real payment economics without a long build, it is among the strongest options available.
Tilled
Tilled publishes its pricing, which almost nobody else on this list does. Below $5 million a month, you keep 70% of the revenue share on a $500 monthly fee. Above that, 80% on $2,500 a month.
This is another option that utilizes revenue share rather than spread ownership, so your upside is capped relative to Rainforest or Finix.
For early- and mid-stage B2B software platforms wanting to monetize payments quickly without upfront cost, that trade is frequently worth taking.
Infinicept
Infinicept is incredibly explicit about the path to full payfac registration, which it has built its positioning around.
Launchpay gets you live in weeks on a managed arrangement; the full enablement program runs three to four months and leaves you considerably closer to owning your own registration.
Infinicept’s model is structured for platforms that plan to eventually own registration and want a defined path to get there.
Payabli
Developer-first, with a no-code onboarding option that can get a platform live in days.
Payabli is smaller and newer than most of this list, which cuts both ways. It is more responsive commercially, but less proven at scale.
Stax Connect
A managed PFaaS offering aimed at software companies that want someone else handling the operational load.
It offers custom pricing and moderate timelines.
Overall, it is a reasonable fit for platforms without a payments team.
Payroc
Payroc has far less brand recognition than Stripe or Adyen, and platforms running competitive processes report that it negotiates more aggressively on buy rate as a result.
It does offer a documented route toward registration, though, and may be worth including in an RFP specifically to put pressure on the incumbents’ pricing.
Matching a provider to your platform
The variable that decides this in practice is your monthly card volume, because it moves both the rate you can get and whether a provider will take the call at all.
Under roughly $150,000 a month: Stripe Connect or Payabli. Flat-rate pricing costs more per transaction, but the basis points you give up are worth less than the engineering weeks you save.
$150,000 to $5 million a month: where spread ownership starts to pay for itself. Rainforest publishes 30 basis points up to $5 million, Finix negotiates wholesale rates, Adyen becomes viable at the bottom of this band, and Tilled’s $500 monthly fee is easy to cover.
Above $5 million a month: tiers move in your favor, and everyone negotiates. Rainforest steps down to 25 and then 20 basis points, Tilled’s share moves to 80%, and full payfac registration starts to be worth modeling rather than dismissing.
Does your vertical change the answer?
Your vertical changes the shortlist more than it changes the economics.
Platforms in healthcare, field services, and other verticals with their own onboarding shape should ask three things a generic comparison skips: whether the provider has underwritten merchants in your vertical before, whether it will sign the agreements your customers’ compliance teams will ask for, and how quickly it activates a sub-merchant whose paperwork is unusual.
A provider that has never underwritten a dental practice or a roofing contractor will not say no. It will just take longer, and the delay lands on your activation numbers rather than theirs.
Split payments and payout logic
If your product pays more than one party out of a single transaction, it’s a good idea to settle this before you compare anything else.
A marketplace taking a commission, a clinic splitting across practitioners, a field services platform paying crews: all of them need the money to land in several places on a schedule you control.
Providers differ on whether the split happens at authorization or at settlement, how many recipients one payment can reach, whether you can hold funds and for how long, and what happens to a split when one leg is refunded.
Those answers shape your ledger design, and finding out late is expensive.
How do the economics actually work?
PayFac-as-a-Service providers take a cut of the volume flowing through your platform, around 20 to 30 basis points, where rates are published. What happens to the rest depends entirely on your commercial model.
Under revenue share, you receive an agreed percentage of the payment margin.
This is very simple and predictable, but it caps your upside permanently. Tilled and the Worldpay revenue-share tier both operate this way.
Under spread ownership, you buy processing at a wholesale interchange-plus rate and set your own merchant pricing. The result is that everything above your cost is yours.
Rainforest, Finix, and Adyen work this way. Just keep in mind that it demands more of you operationally in exchange.
Flat-rate arrangements also exist, and while they could look generous up front, pricing the first three years rather than just the first year tends to change that picture.
The switching cost once merchants are onboarded is real, so run the numbers out to year three before a flat rate decides it for you.
How do you choose a payfac provider?
A sequence that tends to surface the right answer:
Where does the registration sit, and where do merchant losses land? Ask both questions separately. The answers are not always the same.
Revenue share or spread? Decide this before you compare feature tables, because it determines everything downstream.
What is your realistic three-year volume? Model the cost at that number rather than at launch.
Which geographies do you need? Several strong US options do not operate internationally.
Does a path to full payfac registration exist? If you might want it, picking a provider without one guarantees a migration later.
Who underwrites, and how fast? Merchant onboarding friction is where platforms quietly lose activations.
What does the exit look like? Merchant data portability and contract terms matter more than anyone acknowledges at signing.
What is PayFac-as-a-Service?
A payment facilitator holds a master merchant account with an acquiring bank and onboards sub-merchants underneath it.
This means that, rather than each business opening its own merchant account, which traditionally took days and a credit review, the payfac underwrites them and lets them start processing payments almost immediately.
PayFac-as-a-Service lets a software provider offer that experience without becoming a registered payment facilitator.
The provider holds the registration, the sponsor bank relationship, and the core compliance obligations. Your platform only handles merchant onboarding, sets pricing, and owns the customer relationship, but you can earn a share of the payment margin.
Becoming a full payfac requires registration with Visa and Mastercard, partnering with a sponsor bank, adhering to the highest PCI DSS compliance level, underwriting, risk management, and maintaining reserves against merchant losses.
For most software companies, the return does not justify it.
For the definitional version of all this, our explainer on what a payfac actually is walks through the registration, the sponsor bank relationship, and where liability sits.
Why are SaaS platforms adopting payfac as a service?
Payments have very quickly become a revenue line.
Rainforest’s 2026 benchmarking study of vertical SaaS platforms puts the median payments take rate at 53 basis points for platforms early in the journey and 98 for those scaling. Rainforest sells into this market and appears on the list above, so read it with that in mind.
Ambition is running ahead of adoption. The same benchmarking data has 78% of platforms aiming for merchant adoption above 71% within a year or two, while only about a quarter have reached that today.
Adyen and BCG size the embedded finance opportunity for SaaS platforms at $185 billion and reckon less than 20% of it is currently addressed, based on research across North America, Europe and Australia.
Mordor Intelligence sizes the payment facilitation market at $5.62 trillion in 2026, reaching $10.39 trillion by 2031 on a 13% compound rate.
On top of the revenue argument, you need to think about the product one.
A merchant who onboards inside your software, gets paid through your software, and reconciles in your software has a considerably harder time leaving it.
Payments raise switching costs even further, in a way feature releases do not, which tends to show up in retention before it shows up in the P&L.
How does the payfac model actually work?
There are four parties involved in most payfac models.
The card networks set the rules.
An acquiring bank sponsors the payfac.
The payfac holds the master merchant account and onboards sub-merchants.
The sub-merchants accept the payments.
Under payfac-as-a-service, your platform sits between the provider and the sub-merchants.
This means that you collect merchant information, trigger the underwriting the provider performs, and present the whole thing as your own payment system.
The only thing your customer sees is your brand. The registration sits with your provider. The risk divides less cleanly, and the contract decides where it lands.
Three functions determine whether this works operationally.
Onboarding has to be fast enough that merchants do not abandon it, which usually means automated KYC and risk checks rather than manual review.
Risk management has to catch fraud and merchant misconduct before losses accumulate.
Payouts have to settle on a predictable schedule, because nothing erodes trust faster than a merchant not knowing when money arrives.
Teams building this usually need engineers comfortable with payments infrastructure, KYC and AML pipelines, and ledger reconciliation, which is a narrower skill set than general backend work.
What are the levels of payments ownership?
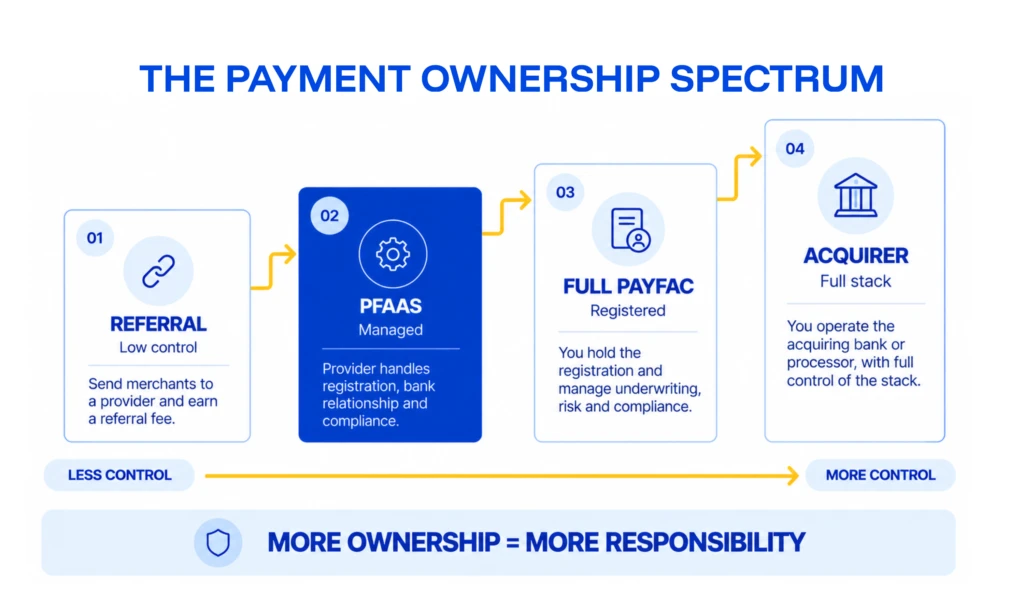
Providers sit on a spectrum in terms of how much payment ownership they hand you:
Referral or ISO: You introduce merchants to a processor and take a commission. Minimal work, minimal revenue, and the processor owns the relationship.
PayFac-as-a-Service: You look like a payment facilitator to your merchants while the provider holds the registration and the heaviest compliance. Margins are materially higher than referral.
Full payfac registration: You hold the registration, the sponsor bank relationship, and the liability. Maximum economics, maximum operational burden, and a project measured in quarters rather than weeks.
Processor or acquirer: Rare for a software company, and generally only sensible at very large scale.
What PayFac-as-a-Service does not solve
While payfac-as-a-service is great, there are definitely some issues that it does not solve.
You still carry risk: The provider holds the registration, and many arrangements still push merchant losses, chargebacks, and fraud exposure onto the platform. Read the reserve and liability terms specifically rather than accepting the summary.
Compliance does not disappear: PCI DSS scope narrows considerably but does not vanish, and your own obligations around data handling, fraud monitoring, and reporting remain yours.
You are taking on an operational function: Someone has to handle merchant support, disputes, failed payouts, and the question of why a specific transaction settled late. Some providers share part of that load, so ask which parts before you assume all of it is yours.
Consolidation is a live risk: Payrix became Worldpay for Platforms, and Worldpay became part of Global Payments within two years. Acquisitions change pricing, roadmaps, and support quality.
Integration is an engineering project: Reconciliation across providers, idempotent webhook handling, and payout ledgering absorb far more time than the onboarding API does.
Building the integration
Choosing a provider completes maybe half the work.
Reconciling payouts into your ledger, handling webhooks idempotently so a retried event never double-credits a merchant, building the merchant-facing reporting, and designing the failure paths all land on your engineering team.
At Trio, we place payment engineers, fintech integrations engineers, and ledger specialists who have shipped this work inside regulated environments, through staff augmentation, dedicated teams, or our fintech engineering practice.
You can see how we work or book a call.