

 Read Client Stories




 Alex Kugell
 Key Takeaways
- Fintech MVP budgets often come in low because they price the engineering and treat compliance as something to figure out after launch.
- The compliance tax, KYC/AML, audit-ready architecture, legal review, and penetration testing typically add 30-40% on top of the engineering-only number, and can be even more expensive later.
- Retrofitting compliance into a product that wasn’t built for it runs roughly three times the cost of building it in from day one.
- The real number to plan around is the two-year total cost of ownership, build plus year-one operating costs, plus the SOC 2 audit that usually lands in year two.
- Engineering is only about half of the total fintech MVP cost. Legal, audits, and compliance tooling cost the same no matter where your engineers sit, which is why nearshore savings land around 22-28% overall rather than the 45-55% you’d see on engineering alone.
We often see fintech founders get a development quote, build a budget around it, and then sit across from an investor who asks why the actual total is double what was pitched.
The reality is that fintech MVPs carry mandatory compliance controls, KYC/AML integration, security architecture built for audits, logging that has to hold up under regulatory scrutiny, and sponsor bank technical due diligence, which general software products simply don’t need.
Depending on product type and regulatory scope, that compliance layer adds $40K to $150K or more on top of the engineering cost.
Leaving it out of the budget doesn’t make it go away. It just defers it, and usually makes it more expensive.
This MVP budget template covers four product types, including payment/wallet, lending, neobank, and wealth/investing, and breaks each one into engineering phases and compliance components.
We’ll also cover the non-engineering line items (legal, audits, tooling) and year-one recurring costs.
Make sure to adjust these values for your actual scope and team model.
If you need affordable engineering talent, sourced from LATAM, with production experience in US markets, get pricing.
How to Use This Template
The ranges below reflect three possible team models: US domestic rates ($120-160/hr for a senior engineer), nearshore LATAM rates ($60-80/hr through a firm like Trio), or a blended model with a US-based tech lead and a LATAM-based team underneath.
Non-engineering line items, compliance tooling, legal, audits, and infrastructure cost roughly the same regardless of where your engineers are.
Pick whichever of the four product templates below is closest to what you’re building, then adjust for scope. If your product spans more than one category, a neobank with embedded lending, say, start from the higher-cost template and layer in the specific components from the lower-cost one.
You will note that each template follows the same structure, with discovery and design, core engineering by phase, QA and security testing, the compliance tax, infrastructure and DevOps setup, and year-one recurring costs.
Template 1: Payment / Wallet App MVP
Payment/Wallet app MPVs could be a wide variety of products, including consumer or B2B payment apps, a digital wallet, a money transfer tool, a bill pay, or a payment acceptance product.
The most noteworthy component of this kind of application is that it handles real money movement and requires KYC plus payment rail integration.
Typical scope will include registration and KYC, funding via bank link or card, send and receive money, transaction history, and usually a single market on a single rail (ACH, FedNow, or Stripe).
Here’s a budget template for LATAM team rates:
| Line item | Low | High | Notes |
| Discovery and design | $8,000 | $18,000 | UX flows, product spec, architecture |
| Backend engineering | $15,000 | $35,000 | APIs, ledger, transaction logic |
| Frontend/mobile | $12,000 | $25,000 | iOS + Android, or web-only at the low end |
| Payment rail integration | $8,000 | $20,000 | ACH baseline; FedNow/RTP adds $15K-25K |
| QA and security hardening | $8,000 | $18,000 | 15-25% of the engineering total |
| KYC/AML integration | $8,000 | $18,000 | Persona, Jumio, Socure, or similar |
| Compliance architecture | $5,000 | $12,000 | Audit logging, SOC 2-aligned data model |
| Legal review | $8,000 | $20,000 | ToS, privacy policy, regulatory filings |
| Penetration testing | $5,000 | $12,000 | Required before launch |
| Infrastructure setup | $5,000 | $10,000 | Cloud provider, CI/CD, monitoring baseline |
| Total MVP build | $82,000 | $188,000 | |
| Compliance overhead | $26,000 | $62,000 | ~32% of the total, the compliance tax |
If you want to make the US rate adjustment, simply multiply engineering line items by 1.8-2.0x. Non-engineering items will stay roughly the same, so the US team’s total will land around $130K-280K.
Payment initiation genuinely adds complexity relative to read-only products. Real-time rails like FedNow and RTP add $15K-25K beyond a baseline ACH build for the added state machine complexity.
Building on a BaaS relationship (Unit, Treasury Prime, Column) adds another $20K-40K.
Template 2: Lending Platform MVP
Lending platform MVPs that we are seeing on the market lately include consumer or B2B lending, personal loans, BNPL, SME lending, and revenue-based financing.
These require credit decisioning, underwriting, loan origination, and repayment management, and often a state lending license or a partner bank arrangement.
Typical scopes cover application plus KYC, credit scoring integration, loan origination workflow, disbursement, repayment tracking, and adverse action notices.
Here’s what that budget template looks like for the LATAM team rates:
| Line item | Low | High | Notes |
| Discovery and design | $10,000 | $20,000 | |
| Backend engineering | $18,000 | $45,000 | Loan lifecycle state machine |
| Frontend/mobile | $10,000 | $22,000 | Application flow, dashboard |
| Credit scoring integration | $5,000 | $15,000 | Experian, Equifax, TransUnion API |
| Disbursement integration | $8,000 | $18,000 | ACH push; FedNow for instant funding |
| QA and security hardening | $10,000 | $22,000 | Underwriting logic testing is critical here |
| KYC/AML and fraud checks | $8,000 | $18,000 | Plus FCRA-compliant adverse action notices |
| Compliance architecture | $8,000 | $18,000 | Reg Z and TILA disclosures, ECOA |
| Legal review | $12,000 | $30,000 | State licensing opinion, loan agreements |
| Penetration testing | $5,000 | $15,000 | |
| Infrastructure setup | $5,000 | $12,000 | |
| Total MVP build | $99,000 | $235,000 | |
| Compliance overhead | $33,000 | $81,000 | ~33% of total |
The US rate adjustment, with engineering line items x 1.8-2.0x, will put the US team total to about $160K-360K.
Lending carries higher compliance costs than payment apps because of Regulation Z (Truth in Lending), the Equal Credit Opportunity Act, the Fair Credit Reporting Act, and state-by-state lending license requirements.
If you’re lending directly rather than through a sponsor bank, budget an additional $15K-50K specifically for state licensing, legal work, AML, and KYC compliance.
Template 3: Neobank / Banking App MVP
A digital banking product, checking, savings, debit card, or a multi-product financial platform is all incredibly complex.
You may require a sponsor bank partnership (Cross River, Coastal, Lead Bank, among others), BaaS middleware (Unit, Treasury Prime, Column), and it carries the deepest compliance requirements of any MVP type on this list.
Typical scopes cover account opening with enhanced KYC, debit card issuance, ACH deposits, P2P transfers, transaction history, and FDIC disclosure engineering.
Here’s a budget template, using LATAM team rates:
| Line item | Low | High | Notes |
| Discovery and design | $12,000 | $25,000 | |
| Backend engineering | $25,000 | $55,000 | Account, ledger, card management |
| Frontend/mobile | $15,000 | $30,000 | |
| BaaS integration | $20,000 | $45,000 | Unit, Treasury Prime, or Column API layer |
| Card program setup | $10,000 | $25,000 | Marqeta or issuer processor integration |
| QA and security hardening | $12,000 | $28,000 | |
| KYC/AML, enhanced | $12,000 | $28,000 | Enhanced due diligence, ongoing monitoring |
| Compliance architecture | $12,000 | $28,000 | BSA/AML program, SOC 2 design |
| Sponsor bank due diligence | $10,000 | $25,000 | Technical and compliance review by the bank |
| Legal review | $15,000 | $35,000 | BaaS agreements, regulatory filings |
| Penetration testing | $8,000 | $18,000 | |
| Infrastructure setup | $8,000 | $15,000 | |
| Total MVP build | $159,000 | $357,000 | |
| Compliance overhead | $57,000 | $134,000 | ~36% of total |
The US rate adjustment of engineering line items (x 1.8-2.0x) takes the total to $240K-530K.
Neobank MVPs carry the heaviest compliance load of any product type here, largely because the sponsor bank runs its own technical due diligence before go-live, expecting $15K-25K in engineering time just to prepare for and pass that review.
Budget 90-120 days for sponsor bank onboarding, specifically. It tends to drive the overall timeline more than the engineering does.
Template 4: Wealth / Investing App MVP
Consumer investing, a robo-advisor, stock trading, fractional shares, or an ETF-based savings product all fall into the category of wealth/investing apps.
These require a broker-dealer relationship or integration with a brokerage API (Alpaca, Tradier, DriveWealth).
The typical scope covers account opening with KYC and a suitability assessment, portfolio configuration, brokerage API integration, order execution, and position tracking.
Here’s the budget template, using LATAM team rates:
| Line item | Low | High | Notes |
| Discovery and design | $12,000 | $25,000 | |
| Backend engineering | $22,000 | $50,000 | Order management, portfolio tracking |
| Frontend/mobile | $15,000 | $30,000 | |
| Brokerage API integration | $12,000 | $28,000 | Alpaca, DriveWealth, Tradier |
| QA and security hardening | $12,000 | $25,000 | |
| KYC + suitability assessment | $10,000 | $22,000 | FINRA-compliant suitability workflow |
| Compliance architecture | $10,000 | $25,000 | SEC/FINRA, Regulation Best Interest |
| Legal review | $15,000 | $35,000 | Investment adviser agreements, disclosures |
| Penetration testing | $5,000 | $15,000 | |
| Infrastructure setup | $8,000 | $15,000 | |
| Total MVP build | $121,000 | $270,000 | |
| Compliance overhead | $40,000 | $97,000 | ~33% of total |
US rate adjustment: engineering x 1.8-2.0x. US-team total runs $190K-410K.
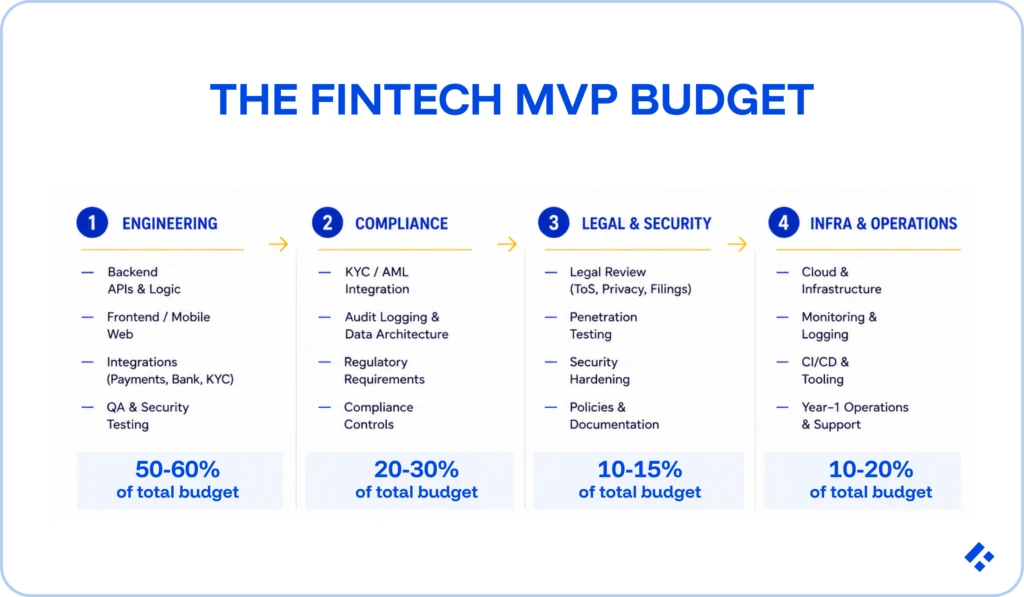
The Compliance Tax
Every budget table above separates compliance costs into their own category on purpose.
We have done this because it’s consistently the most underestimated line item in fintech MVP planning, typically adding 30-40% on top of the engineering-only number.
Understanding what it’s actually made of is what helps you create a credible budget.
- KYC/AML integration: Third-party identity verification (Persona, Jumio, Socure, Alloy, among others) plus the engineering to wire it into your onboarding flow. Roughly $8K-28K, depending on product complexity and vendor.
- Compliance architecture: Audit-ready logging with immutable event records, a SOC 2-aligned data model, and access control and encryption decisions made correctly from day one rather than bolted on later. Roughly $5K-28K.
- Sponsor bank due diligence (for neobank and payment products specifically): The engineering preparation and technical review that a sponsor bank requires before approving the BaaS relationship. Roughly $10K-25K.
- Legal review: Terms of service, privacy policy, regulatory filings, and specialist fintech legal counsel on whatever framework actually applies to your product: BSA/AML, Reg Z, ECOA, Reg BI. Roughly $10K-35K.
- Penetration testing: A third-party security assessment that most banking partners require before launch, and that enterprise customers increasingly expect too. Roughly $5K-18K.
- Compliance tooling: Ongoing transaction monitoring, sanctions screening, SAR filing support, and general compliance workflow tools (Sardine, Unit21, ComplyAdvantage, and similar). Roughly $500-5,000 a month, ongoing.
- Regulatory reserve: A 20-30% contingency on top of your estimated compliance cost. Regulatory requirements aren’t fully known until you actually engage the sponsor bank, the regulator, or compliance counsel who reviews your specific product, so budget the uncertainty explicitly instead of hoping it doesn’t show up.
While this may seem expensive up front, skipping the compliance tax in your initial budget doesn’t save that money. It defers it, at triple the price, to a moment you don’t get to choose.
Year-One Recurring Costs: The Budget Beyond Launch
Your MVP budget might take you to the launch, but what comes after is often equal to or larger than the build cost.
| Category | Monthly | Annual |
| Cloud infrastructure (baseline) | $500-3,000 | $6K-36K |
| Compliance monitoring tooling | $500-3,000 | $6K-36K |
| KYC/AML verification (per-check fees) | Volume-based | $5K-30K |
| Engineering maintenance (~20-25% of build) | – | $20K-70K (LATAM rates) |
| SOC 2 Type II audit, all-in first year (year two onward) | – | $25K-100K |
| PCI DSS certification (if card data is in scope) | – | $5K-80K, depending on SAQ level and how much you’ve reduced the scope through tokenization |
| Legal / compliance counsel | $1,500-5,000 | $18K-60K |
| Security monitoring / SIEM | $200-1,000 | $2.4K-12K |
| Total year-one recurring | $3,000-13,500/month | $36K-165K |
A note on that SOC 2 line specifically: the audit fee itself typically runs $10K-60K for a startup-scale Type II engagement.
What is represented above is the all-in first-year figure, made up of the audit, readiness assessment, compliance tooling, and internal engineering time.
Treat anything below $20K as likely missing a real cost component, and anything above $150K as enterprise-scale scope, multiple Trust Service Criteria, and a Big Four auditor, which most seed and growth-stage fintechs don’t need yet.
The LATAM Engineering Adjustment
The engineering line items above already assume a LATAM team. These are the only items that are location-dependent and can be roughly 25-35% cheaper than US domestic rates.
Backend engineering, frontend and mobile engineering, integration engineering (payment rails, BaaS, brokerage APIs), QA and security hardening, and compliance architecture engineering are just some examples of where you can take advantage of these cost savings.
Location-independent factors, which are the same cost regardless of where the team sits, include legal review, third-party penetration testing, compliance tooling subscriptions, infrastructure and cloud costs, SOC 2 and PCI DSS audits, and sponsor bank due diligence.
Engineering usually runs roughly half of the total MVP cost. At a 45-55% engineering cost reduction against US domestic rates, that works out to a 22-28% reduction in total MVP cost.
Hiring engineers who’ve actually built fintech products in production means they tend to already know that audit logging has to be immutable, that a KYC flow needs to be a real state machine rather than a boolean flag, and that payment idempotency belongs in the first version.
Trio places pre-vetted LATAM fintech engineers, with the production domain experience that removes the compliance retrofit risk described above, in 3-5 days at $40-80/hr.
To get started, request a budget consult.